
Blogs
PW Consulting: Global Email Address Verification Service Market to Reach $4,305.78 Million by 2032 at 13.45% CAGR
By pmarketresearch, 2026-09-16
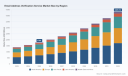
Strategic Imperative: Navigating the Global Email Address Verification Service Market 2026–2032
In the contemporary digital economy, data quality is not merely an operational metric; it is a foundational asset that dictates the efficiency of marketing spend, the integrity of customer communication, and the overall health of an organization's digital infrastructure. As enterprises increasingly rely on automated outreach and digital engagement models, the risk of data decay poses a significant threat to revenue generation. PW Consulting is pleased to introduce our latest comprehensive market research, Worldwide Email Address Verification Service Market, designed to equip decision-makers with the critical intelligence needed to navigate this evolving landscape through 2032.
This report serves as a strategic compass for stakeholders aiming to understand the trajectory of the email verification industry. By analyzing historical performance from 2020 to 2025 and projecting trends through the forecast period of 2026 to 2032, we provide a granular view of market drivers, regulatory pressures, and competitive dynamics. The following insights highlight the strategic value of this research for enterprise planning in 2026 and beyond.
Market Trajectory and Revenue Outlook
The global market for email address verification services is experiencing robust growth, driven by the escalating need for data hygiene and deliverability optimization. Our analysis indicates that the market has transitioned from a niche utility to a core component of enterprise technology stacks. In the base year of 2025, the overall market revenue reached approximately 1,780.0 Million USD. This figure underscores the substantial financial commitment organizations are making to ensure their communication channels remain open and effective.
Looking forward, the growth trajectory remains steep. The market is projected to expand significantly over the next seven years. By the end of the forecast period in 2032, the revenue landscape is expected to shift dramatically, reflecting both organic adoption and the integration of verification tools into broader data management platforms. The compound annual growth rate (CAGR) observed during this forecast window stands at 13.45%, signaling a high-velocity environment where early movers and strategic investors can capture significant value.
In the immediate term, the market size for 2026 is estimated to reach 2,019.41 Million USD. This milestone represents a critical inflection point where verification services are no longer optional add-ons but essential compliance and operational requirements. As we move further into the decade, reaching 2027 and beyond, the cumulative growth will reflect the maturation of API-driven verification and the increasing sophistication of bulk cleaning technologies.
Key Market Drivers and Structural Dynamics
Several converging factors are propelling this market expansion. First, the cost of email bounces and spam complaints has risen sharply. Internet Service Providers (ISPs) and mailbox providers have tightened their filtering algorithms, making high sender reputation a prerequisite for campaign success. Organizations that fail to validate their lists face not only wasted marketing budgets but also the risk of domain blacklisting, which can cripple critical business communications.
Second, the regulatory environment has become increasingly stringent. Privacy laws such as the General Data Protection Regulation (GDPR) in Europe and the California Consumer Privacy Act (CCPA) in the United States have reclassified email addresses as personal data. This classification imposes strict obligations on how data is collected, processed, and cleaned. For instance, GDPR enforcement has resulted in average fines around 2.8 Million EUR in recent years, with maximum penalties reaching up to 20 Million EUR or 4% of global turnover. Similarly, the California Privacy Protection Agency increased monetary damages and administrative fines effective January 1, 2025, aligning penalties with Consumer Price Index adjustments.
Worldwide Email Address Verification Service Market
Third, the operational cost of compliance is a significant consideration. Initial GDPR compliance for small businesses with email marketing activities typically costs between 5,000 and 30,000 EUR in the first year, covering policies, data mapping, and tools. Email verification services help mitigate these risks by ensuring that data processing aligns with lawful consent requirements. Furthermore, the California Privacy Protection Agency approved updated CCPA regulations on cybersecurity audits and risk assessments in 2025, increasing compliance obligations for data processors, including verification services. These regulatory pressures force organizations to adopt robust verification protocols to avoid legal exposure and financial penalties.
Verification Types and Organizational Adoption
The market is segmented by verification methodologies, primarily distinguishing between real-time API verification and bulk email verification. Real-time API verification allows organizations to validate email addresses at the point of entry, such as during sign-up forms or checkout processes. This proactive approach prevents invalid data from entering the database in the first place. Bulk email verification, on the other hand, is utilized for cleaning existing databases. This method is critical for marketing teams preparing large-scale campaigns or re-engaging dormant contacts. Both segments play complementary roles in a comprehensive data hygiene strategy, with adoption rates varying based on organizational maturity and specific use cases.
Organization size also influences adoption patterns. Large enterprises typically possess the resources to implement enterprise-grade verification solutions with deep integrations into Customer Relationship Management (CRM) systems and marketing automation platforms. These organizations often have complex data ecosystems requiring scalable solutions. Small and medium enterprises (SMEs) also represent a significant portion of the market, driven by the need to optimize limited marketing budgets and improve deliverability without heavy infrastructure investment. The accessibility of pay-as-you-go models and user-friendly interfaces has lowered the barrier to entry for smaller players, expanding the total addressable market.
Competitive Landscape and Vendor Differentiation
The competitive environment is characterized by a mix of specialized validation providers and broader data intelligence platforms. Market concentration indicates a moderately fragmented landscape, though consolidation trends are observable. Key players are differentiating themselves through accuracy, speed, compliance certifications, and integration capabilities.
Major vendors in this space include ZeroBounce, headquartered in Boca Raton, Florida, which provides accurate real-time email validation API, bulk list cleaning, deliverability analytics, and scoring to reduce bounces and improve inbox placement for marketing and sales teams. Similarly, NeverBounce, based in Vancouver, Washington and part of ZoomInfo, specializes in email validation, data hygiene, bulk cleaning, and CRM integrations with high accuracy for agencies and scalable email campaigns.
International players are also making significant strides. Hunter.io, based in Belgium, delivers an email finder combined with verification tools, bulk verifier, and real-time API for B2B lead generation and list hygiene to support outbound sales and marketing. Clearout, operating from India with global reach, offers an AI-powered email validation, finder, and prospecting platform with bulk verification, risk scoring, and Google Sheets integration for improved deliverability. Bouncer, based in Poland, offers bulk email verification, real-time API validation, and compliance-focused services including ISO 27001 certification for secure email list cleaning and deliverability optimization.
Other notable contributors include Kickbox and Emailable in the United States. Kickbox provides real-time and bulk email verification API with strong integrations to Email Service Providers (ESPs), focusing on deliverability, catch-all detection, and pay-as-you-go pricing. Emailable offers fast bulk and real-time email verification with high accuracy, spreadsheet uploads, and integrations for marketing automation and list cleaning. Additionally, Verifalia in Italy provides real-time email validation API and bulk verification with SDKs for multiple platforms, emphasizing discreet processing and high accuracy. MillionVerifier and EmailListVerify also serve the market with a focus on affordable bulk email list cleaning and real-time API verification optimized for high-volume users and cost-effective hygiene for SMBs and enterprises seeking accurate, no-frills validation.
Recent Developments and Innovation Trends
Innovation in this sector is accelerating, particularly around artificial intelligence and compliance security. In March 2026, Clearout announced an AI Feature Enhancement, introducing advanced AI-powered bulk email verification with enhanced risk detection and predictive deliverability scoring using machine learning and over 20 validation checks. This move highlights the industry's shift towards predictive analytics rather than simple syntax checking.
In April 2026, Hunter.io released a Benchmark Study, publishing independent benchmark testing of 15 email verifiers on real business emails, highlighting accuracy metrics for enterprise validation. Such transparency drives quality standards across the industry. Furthermore, in March 2026, Bouncer emphasized ISO 27001 certification and strong catch-all detection in 2026 tool comparisons for security-focused email validation. These developments suggest that security certifications and advanced risk scoring are becoming key differentiators for enterprise buyers who prioritize data security alongside deliverability.
Regional Insights and Growth Opportunities
Geographically, the market exhibits varied growth patterns driven by digital maturity and regulatory frameworks. North America remains a dominant force in the global landscape, reflecting high digital advertising spend and early adoption of advanced data hygiene tools. Europe follows closely, propelled by strict data privacy regulations that necessitate rigorous verification protocols to ensure compliance with GDPR and related directives.
The Asia Pacific region represents a high-growth opportunity, fueled by expanding digital economies and increasing internet penetration. As businesses in this region scale their digital marketing efforts, the demand for reliable verification services is expected to rise. Latin America and the Middle East and Africa are also emerging markets, though adoption rates may vary based on local infrastructure and economic conditions. Understanding the specific regulatory and economic nuances of each region is critical for vendors looking to expand their footprint and for organizations managing global data operations.
Strategic Recommendations for 2026 Decision-Makers
As organizations plan their technology investments for 2026 and beyond, several strategic actions are recommended based on our market analysis. First, prioritize integration capabilities. Verification tools should not operate in silos; they must integrate seamlessly with existing CRM, marketing automation, and customer data platforms to ensure real-time data hygiene across the organization.
Second, evaluate vendors on compliance credentials. Given the escalating regulatory fines and the classification of email data as personal information, selecting a provider with robust security certifications and clear data processing policies is essential. Look for ISO certifications and adherence to major privacy frameworks.
Third, consider the total cost of ownership beyond subscription fees. While some providers offer low-cost bulk cleaning, the hidden costs of poor accuracy, such as wasted ad spend, damaged sender reputation, and compliance risks, can far exceed the initial savings. Invest in solutions that offer predictive scoring and comprehensive validation checks.
Email Deliverability Services Market
Finally, stay informed on market consolidation. As the market matures, we may see acquisitions or mergers among key players. Maintaining flexibility in vendor contracts and staying abreast of industry shifts will ensure that your organization can adapt quickly to changes in the competitive landscape.
Conclusion
The Worldwide Email Address Verification Service Market is poised for significant expansion, driven by technological innovation, regulatory pressure, and the fundamental need for data integrity. PW Consulting's latest research provides the depth and breadth of analysis required to make informed strategic decisions in this dynamic environment. From macroeconomic trends to competitive profiling and regulatory impacts, this report offers a holistic view of the industry.
To access the full detailed segmentation data, comprehensive vendor profiles, and exclusive forecasts that underpin these insights, we invite you to explore the complete report on our website. Equip your organization with the intelligence needed to secure your data infrastructure and maximize engagement efficiency in the years ahead.
For detailed analysis of this topic, please visit the official page: Worldwide Email Address Verification Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Industrial Flexible Hose Market Hits $15.74B in 2025, Forecasting 5.12% CAGR to 2032
By pmarketresearch, 2026-09-16
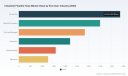
Strategic Imperatives in the Global Industrial Flexible Hose Market 2026-2032
The global industrial landscape is undergoing a profound transformation driven by infrastructure expansion, energy transition projects, and stringent safety regulations. At the heart of fluid transfer systems lies the industrial flexible hose, a critical component that ensures operational continuity across sectors ranging from oil and gas to food processing. For executives and strategy leaders, understanding the trajectory of this market is not merely about tracking sales figures; it is about anticipating supply chain resilience, material innovation, and competitive positioning. This analysis draws upon comprehensive research to outline the strategic value of the Worldwide Industrial Flexible Hose Market study, offering a roadmap for decision-makers navigating the forecast period from 2026 to 2032.
Market Trajectory and Macro Economic Drivers
The industrial flexible hose market has demonstrated consistent resilience and growth over the past half-decade. Historical data indicates a steady climb in revenue, with the market valuation rising from approximately 12,050 million USD in 2020 to an estimated 15,744 million USD in 2025. This upward trend reflects the compounding effects of industrial automation, increased hydraulic system complexity, and the replacement cycle of aging infrastructure. As we look toward the forecast period, the momentum is expected to continue, with projected revenues reaching over 22,331 million USD by 2032.
The compound annual growth rate (CAGR) during the forecast period is estimated at 5.12 percent. This moderate yet robust growth rate suggests a maturing market that is still expanding due to fundamental industrial demand rather than speculative bubbles. Several macro drivers are fueling this expansion. Notably, global oil and gas capital expenditure is projected to hit significant levels in 2025, directly boosting demand for chemical-resistant flexible hoses capable of withstanding harsh environments. Additionally, the manufacturing sector continues to prioritize efficiency and safety, driving adoption of high-performance hose assemblies that reduce downtime and maintenance costs.
However, growth is not without friction. Raw material volatility remains a key concern for procurement leaders. Natural rubber prices averaged around 1,800 USD per metric ton in the fourth quarter of 2024, marking an increase due to supply constraints in Southeast Asia. Similarly, PTFE resin prices rose significantly driven by competing demand from the semiconductor sector. These input cost pressures necessitate strategic sourcing and may influence pricing strategies across the value chain. Furthermore, regulatory updates such as the ISO 1436 standard revisions impose stricter requirements on rubber hoses used in petroleum-based hydraulic fluids, forcing manufacturers to adapt compliance protocols quickly.
Segmentation Dynamics and Operational Implications
Understanding where value is generated within the market is crucial for targeted investment. The market structure is defined by distinct segmentation splits including region, material, and end-user industry. In terms of material composition, the landscape is diversified. Rubber continues to hold a significant share due to its versatility and durability in high-pressure applications. PVC remains a cost-effective solution for lighter duty transfers, while Polyurethane is gaining traction for its abrasion resistance. Metal hoses are essential for high-temperature and corrosive environments, and composite materials are emerging for specialized technical applications.
Industrial Hose Market
End-user industry segmentation reveals where the demand originates. The oil and gas sector remains a dominant force, driven by upstream and downstream fluid transfer needs. Chemical processing follows closely, requiring hoses that meet rigorous safety and contamination standards. Food and beverage applications demand hygienic designs, while the automotive and agriculture sectors rely on durable hydraulic and fluid lines. Pharmaceuticals require high-purity solutions, often pushing the adoption of specialized materials like PTFE. Each segment presents unique technical requirements and procurement cycles, making a one-size-fits-all strategy ineffective.
Regional dynamics also play a pivotal role in market access. Asia Pacific represents a substantial portion of market activity, reflecting rapid industrialization and infrastructure development. North America and Europe maintain mature markets with high emphasis on replacement demand and regulatory compliance. Latin America and the Middle East and Africa offer growth opportunities tied to energy exploration and agricultural output. For multinational corporations, aligning distribution networks and local manufacturing capabilities with these regional variances is essential for capturing market share.
Competitive Landscape and Strategic Positioning
The market is characterized by a fragmented yet competitive landscape. The concentration of market share among the top players indicates a competitive environment where differentiation is key. The top three companies account for roughly 18.45 percent of the market, while the top five hold approximately 28.12 percent. This suggests that while large players dominate, there is significant room for specialized manufacturers and regional leaders to thrive through niche specialization and service excellence.
Several key companies define the competitive edges of this industry. Gates Corporation, headquartered in Denver, is a leading global manufacturer of industrial rubber and thermoplastic hoses, particularly strong in mining and construction sectors. Parker Hannifin Corporation, based in Cleveland, provides a comprehensive range of hydraulic and pneumatic solutions, recently enhancing its portfolio with the launch of the 7100FC thermoplastic hose series for mining and construction in March 2024, featuring enhanced abrasion resistance. Eaton Corporation, from Dublin, offers Aeroquip branded hoses for heavy-duty applications and exhibited Weatherhead hydraulic hoses at MINExpo International in September 2024.
Continental AG and Trelleborg Group represent significant European strength. Continental's ContiTech division focuses on conveying liquids and gases in chemical and petrochemical industries. Trelleborg specializes in polymer-based hoses for high-temperature and corrosive media, showcasing new Trigear hybrid hoses at the Offshore Technology Conference in April 2024 for subsea applications. In Asia, Yokohama Rubber and Bridgestone Corporation leverage their material science expertise for marine and construction applications. Bridgestone offers industrial hoses through its Firestone brand for air and chemical transfer.
Worldwide Industrial Flexible Hose Market
Specialized manufacturers also play a critical role. Alfagomma from Italy manufactures hydraulic hoses for construction machinery, while Manuli Hydraulics produces thermoplastic and hybrid hoses for mining and oil and gas. Goodall Rubber Company in the USA custom manufactures rubber and PVC hoses for chemical and food industries. Novaflex in Canada produces ducting and rubber hoses for ventilation and material handling. Aflex Hose Ltd in the UK specializes in PTFE flexible hoses for high-purity applications. Regional players like Ryco Hydraulics in Australia and Pacific Hoseflex supply critical support for Asia-Pacific markets and high-pressure industrial uses respectively. Strategic partnerships, acquisitions, and product innovation among these entities will shape the competitive intensity in the coming years.
Industry Dynamics and Risk Management
Beyond the raw numbers, the operational environment is shifting. Labor costs in key manufacturing hubs are rising. For instance, US manufacturing labor costs for hose assembly increased by 4.2 percent to 28.50 USD per hour in 2024. This trend pressures margins and encourages automation in assembly lines. Companies must evaluate whether near-shoring or investing in automated production technology offers a better return on investment compared to traditional labor-intensive models.
Innovation cycles are accelerating. Recent developments highlight a focus on durability and specific application performance. Gates Corporation introduced the MegaBlast mining hose in November 2023 with 20 percent higher burst pressure for underground operations, addressing safety and efficiency in extraction industries. These product launches signal to the market that performance metrics are shifting toward higher pressure ratings and longer service life. Companies that fail to align their R and D pipelines with these emerging performance standards risk losing relevance in high-value segments.
Supply chain security is another dynamic element. The reliance on specific raw materials like natural rubber and PTFE creates vulnerability to geopolitical and environmental disruptions. Mitigation strategies involve diversifying supplier bases and investing in alternative material research. Furthermore, regulatory compliance is not static. The update to ISO 1436 requires ongoing vigilance to ensure product certifications remain valid across different jurisdictions, especially for exporters dealing with multiple regulatory frameworks.
Strategic Value of Comprehensive Market Intelligence
For organizations operating in this space, generic market overviews are insufficient. Decision-makers require granular intelligence that connects market size data with actionable strategy. The full research report provides detailed segmentation analysis that goes beyond high-level aggregates. It offers specific insights into volume trends, pricing mechanisms, and regional growth hotspots that are not visible in summary data. Access to this depth allows procurement teams to negotiate better contracts, sales teams to identify untapped territories, and R and D departments to prioritize technologies with the highest commercial potential.
The report also covers competitive profiling in depth, analyzing the strategic moves of the key companies mentioned earlier. Understanding the product launch cadence and trade show presence of competitors like Parker, Trelleborg, and Gates helps in benchmarking internal performance and anticipating market shifts. Moreover, the inclusion of raw material price trends and labor cost data enables more accurate financial forecasting and risk assessment models.
Investing in this level of market intelligence is an investment in operational agility. In a market projected to grow to over 22 billion USD by 2032, the difference between market share gain and loss often comes down to timing and precision. Knowing exactly which material segments are expanding in which regions, or how regulatory changes will impact specific end-user industries, allows companies to pivot resources before competitors react. The 5.12 percent CAGR indicates steady growth, but the distribution of that growth is uneven across segments and geographies.
Conclusion and Call to Action
The Worldwide Industrial Flexible Hose Market presents a landscape of stable growth tempered by complex operational challenges. From raw material volatility to regulatory compliance and competitive innovation, the factors influencing success are multifaceted. While the aggregate data suggests a healthy trajectory with revenues climbing toward 22,331 million USD by 2032, the real value for enterprise strategy lies in the details beneath the surface. Understanding the specific drivers in oil and gas capex, the implications of ISO standards, and the competitive maneuvers of industry leaders is essential for crafting robust strategies.
To fully capitalize on the opportunities within this forecast period, stakeholders need access to the complete dataset and analytical frameworks provided in the full study. The summary provided here outlines the structural dynamics and competitive environment, but the specific segmentation splits, precise regional valuations, and detailed company profiling contained in the full report are critical for executable planning. We invite you to access the source webpage to obtain the comprehensive intelligence required to navigate the 2026-2032 period with confidence. Securing this data is the first step toward optimizing your supply chain, refining your product portfolio, and securing a competitive advantage in the global industrial flexible hose market.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Flexible Hose Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Composite Railroad Tie Market Hits $943.15M in 2025, Projected 6.12% CAGR Through 2032
By pmarketresearch, 2026-09-16
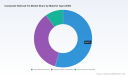
Navigating the Next Decade: Strategic Insights from the Worldwide Composite Railroad Tie Market
The global railroad infrastructure sector stands at a pivotal intersection of sustainability mandates, lifecycle cost optimization, and material innovation. For executives, capital allocators, and procurement leaders operating in 2026, the decision to commit to traditional timber, concrete, or advanced composite sleepers is no longer a purely technical evaluation. It is a strategic imperative shaped by regulatory shifts, supply chain resilience requirements, and rapidly maturing field validation data. The recently published Worldwide Composite Railroad Tie Market research report delivers a comprehensive intelligence framework designed to translate these complex forces into actionable strategy. This overview illuminates the report's architectural depth and its direct relevance to enterprise decision-making in the current operating environment.
Worldwide Composite Railroad Tie Market
Market Trajectory and the 2026 Inflection Point
Tracking the evolution of the composite railroad tie segment from 2020 through the present reveals a clear acceleration curve. Over the past half-decade, market valuation expanded from a baseline of approximately 712 million USD to a projected 2026 valuation of roughly 1,001 million USD. The trajectory continues its upward momentum across the forecast horizon, reaching an estimated 1,429 million USD by 2032, underpinned by a compound annual growth rate of 6.12 percent. These figures are not merely illustrative of sector growth; they signal a structural reallocation of capital toward materials that offer extended service intervals, reduced maintenance footprints, and compatibility with circular economy objectives.
For operators managing extensive network portfolios, the inflection represented by this growth curve demands rigorous scenario planning. The transition from reactive replacement cycles to proactive infrastructure hardening requires visibility into how material adoption scales across different track classifications, climate zones, and freight/passenger mix profiles. The report dissects the historical performance data alongside forward-looking utilization models, enabling leadership teams to calibrate procurement timing, capex phasing, and vendor qualification roadmaps against realistic adoption curves rather than speculative projections.
Strategic Content Architecture: From Data to Execution
A market intelligence publication only creates enterprise value when it bridges the gap between macro indicators and ground-level operational variables. This research report is engineered to function as a working decision-support system. The analysis begins with a granular examination of material composition dynamics, evaluating how fiber-reinforced polymer formulations, recycled plastic composite architectures, and rubber-based composite variants perform across load-bearing requirements, environmental exposure profiles, and installation logistics. Rather than treating material categories as static silos, the report maps performance differentiators against real-world track conditions, providing clarity on where specific composite formulations deliver defensible return on investment.
The analytical framework extends into application-specific deployment modeling. Mainline railway corridors, transit and metro networks, and industrial and mining environments each impose distinct thermal, vibration, and dwell-time stresses on sleeper systems. The report correlates historical installation data with operational outcomes, helping engineering and asset management teams anticipate where composite ties can compress maintenance cycles, reduce track geometry degradation, and extend the interval between replacement campaigns. This application-level perspective is critical for procurement teams evaluating whether composite integration aligns with the duty cycles of specific line segments or rolling stock profiles.
Beyond material and application mapping, the publication integrates regulatory and sustainability overlays that are reshaping procurement evaluation criteria. Environmental compliance frameworks, creosote treatment phase-outs, and corporate decarbonization commitments are no longer peripheral considerations. They now function as primary drivers of specification adjustments and vendor selection matrices. The report quantifies the directional influence of these policy vectors on procurement behavior, giving executives the context needed to anticipate specification changes before they disrupt bidding timelines or create supply gaps.
Competitive Dynamics and Ecosystem Positioning
The composite railroad tie landscape is characterized by a concentrated yet highly differentiated competitive field. The report provides detailed profiling of the organizations actively shaping technology standards, scaling production capacity, and securing specification approvals across major rail networks. Companies such as Evertrak LLC, Sicut Enterprises, Pioonier GmbH, and TieTek have established distinct market positions through combinations of patented processing methods, certification achievements, and targeted deployment campaigns in high-decay or heavy-haul environments. Their track records illustrate how material engineering, regulatory compliance, and field trial execution converge to build commercial momentum.
International players further complicate and enrich the competitive mosaic. AGICO's cost-competitive synthetic sleeper programs for metro and high-speed applications, Triton Group's fiber-reinforced polymer portfolio, and Sekisui Chemical's long-standing presence in synthetic sleeper technology each demonstrate how regional manufacturing capabilities and material specialization influence specification adoption. Organizations such as Axion Structural Innovations, IntegriCo Composites, Lankhorst Mouldings, and Vossloh contribute additional layers of differentiation, whether through recycled-content formulations, concrete-composite hybrid offerings, or CO2-optimized design approaches tailored to project-specific requirements.
The report does more than catalog these entities. It evaluates coordination patterns, partnership architectures, and certification pathways that determine which suppliers can scale reliably in Class I railroad environments, transit authorities, and industrial freight corridors. By examining the intersection of proprietary technology claims, field trial outcomes, and procurement qualification status, the analysis helps sourcing leaders distinguish between marketing narratives and commercially deployable solutions. This distinction is essential when evaluating long-term supply continuity, warranty risk, and total cost of ownership across multi-year infrastructure programs.
Fiberglass Composite Rail Ties Market
Recent Developments and Strategic Implications for 2026
Several recent events have materially altered the operating context for composite tie deployment, and the report incorporates these developments into its forward-looking assessment. In April 2026, Progress Rail, as a Caterpillar company, entered into an agreement with Triton Group to serve as the exclusive seller and marketer of Triton's composite railroad tie technology. This arrangement couples specialized materials expertise with broader engineering capabilities and global distribution reach, signaling a strategic push to improve track reliability, reduce environmental impact, and lower lifecycle costs through coordinated commercialization.
Field validation activity has also intensified. A large-scale trial involving Norfolk Southern in 2025 saw the installation of approximately 30,000 glass-reinforced polymer composite sleepers sourced from multiple manufacturers, achieving a 100 percent installation success rate at conventional deployment speeds. Additional installation activity noted with BNSF and CSX, alongside pending approvals for Union Pacific, reflects a broader pattern in which major Class I railroads are expanding trial scope and moving toward broader adoption to address wood tie decay in high-humidity regions while targeting reduced long-term maintenance and replacement expenditures.
Capital and supply chain movements further illustrate the sector's maturation. In early 2025, Sumitomo Corporation made a strategic investment in Evertrak to support expanded production capacity for glass fiber reinforced polymer composite ties manufactured from recycled plastics, reinforcing the alignment between sustainability goals and North American infrastructure demand. Meanwhile, procurement policy shifts in the United Kingdom, including the termination of hardwood and softwood sleeper procurement by Network Rail executive leadership and the subsequent capability transfer to composite alternatives following full product approval and track trials, demonstrate how regulatory and environmental strategies can rapidly reshape supplier landscapes and create new specification defaults.
For strategy teams, these developments are not isolated news items. They represent structural signals about where specification authority is moving, which partnerships are likely to influence distribution and service coverage, and how quickly field validation can translate into procurement volume. The report synthesizes these dynamics into scenario-based guidance, allowing decision-makers to evaluate how partnership structures, trial outcomes, and policy transitions might affect supply availability, lead times, and competitive positioning over the forecast period.
Why This Intelligence Matters for Decision-Makers
Enterprise leaders evaluating infrastructure material strategies in 2026 need more than headline growth figures. They need to understand where concentration risk resides, how certification and performance standards filter supplier eligibility, and which operational variables determine whether composite integration delivers the expected reduction in maintenance exposure. The market exhibits meaningful concentration, with the top three firms accounting for a substantial share of revenue and the top five firms extending that coverage further. This concentration has direct implications for procurement diversification, supply continuity planning, and negotiation leverage. The report provides the analytical context required to interpret these concentration patterns without over-simplifying the underlying competitive differentiation.
Equally important is the need to align material selection with environmental and lifecycle performance expectations. Advanced composite ties increasingly incorporate post-consumer recycled plastics reinforced with glass fibers, supporting diversion of plastic waste from landfills while meeting or exceeding recognized strength and stiffness standards. Some products have achieved industry certification benchmarks and demonstrated extended service life in high-decay zones, contrasting sharply with the shorter replacement intervals associated with traditional timber. The report connects these performance and sustainability attributes to procurement economics, enabling asset managers to evaluate whether lifecycle cost reductions, regulatory compliance benefits, and circular-economy alignment justify specification changes within their specific operating environments.
The forecast window through 2032 offers additional strategic utility. By mapping anticipated revenue expansion alongside the underlying material, application, and regional adoption variables, the report helps leadership teams anticipate demand pressure points, capacity constraints, and specification migration timelines. This forward view supports capital planning, vendor onboarding schedules, and internal business case development for composite integration projects, ensuring that investment decisions are tied to defensible adoption trajectories rather than optimistic assumptions.
Conclusion: Turning Market Intelligence into Infrastructure Advantage
The Worldwide Composite Railroad Tie Market research report is designed for organizations that treat infrastructure material strategy as a long-duration competitive variable rather than a routine purchasing function. By combining macro market sizing, material and application differentiation, competitive profiling, and recent partnership and trial developments into a single analytical framework, the publication equips executives to make procurement, investment, and specification decisions with greater confidence. The data trajectory, competitive dynamics, and policy-driven adoption signals discussed here represent only the entry layer of the full analysis. Organizations seeking to evaluate exact market size breakdowns, segment-level utilization models, supplier positioning matrices, and forecast-driven procurement scenarios will find the complete report essential to aligning their 2026 and beyond strategies with the realities of a rapidly evolving composite tie landscape.
For detailed analysis of this topic, please visit the official page: Worldwide Composite Railroad Tie Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Low-Frequency Geophone Market Hits $152.45M in 2025, 7.0% CAGR to $244.81M by 2032
By pmarketresearch, 2026-09-16
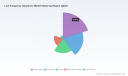
Navigating the Worldwide Low Frequency Geophone Market: Strategic Intelligence for 2026 Decision-Making
The global landscape for seismic instrumentation is entering a critical phase of recalibration. As energy transition projects, advanced geophysical research, and industrial safety monitoring converge, the demand for reliable low frequency geophones has moved from a niche technical requirement to a strategic infrastructure priority. For executives, procurement leaders, and technology strategists operating in 2026, understanding the trajectory of this market is no longer optional. It is a prerequisite for capital allocation, supply chain resilience, and competitive positioning.
Our newly published Worldwide Low Frequency Geophone Market research study provides a comprehensive, data-backed roadmap through the 2026 to 2032 forecast period. Designed for executive briefing and operational planning, this report bridges historical performance with forward-looking intelligence, enabling organizations to anticipate demand shifts, evaluate vendor ecosystems, and align technology roadmaps with emerging geophysical applications.
Market Trajectory: From Historical Foundations to Forward Momentum
The worldwide low frequency geophone sector has demonstrated consistent expansion over the past half-decade, reflecting both mature industrial adoption and emerging use cases tied to environmental monitoring and deep-earth exploration. Historical revenue tracking from 2020 through the 2025 base year reveals a steady upward curve, culminating in a market valuation of approximately 152.45 million USD. This foundation has set the stage for a projected growth trajectory that extends well into the next decade, with the market anticipated to reach 244.81 million USD by 2032.
Underlying this expansion is a compound annual growth rate of 7.0 percent, a metric that signals more than incremental demand. It reflects structural shifts in how organizations approach subsurface imaging, seismic hazard assessment, and long-term infrastructure monitoring. The forecast window from 2026 onward captures the inflection point where traditional oil and gas workflows increasingly intersect with carbon storage verification, induced seismicity tracking, and remote-deployed sensing networks. Organizations that recognize this dual-engine growth pattern will be better positioned to hedge against cyclical commodity exposure while capturing value from sustained scientific and industrial procurement.
The historical data also underscores a market that has matured beyond early-adopter experimentation. Revenue patterns from 2020 to 2025 demonstrate how supply chains, manufacturing tolerances, and frequency-response engineering have stabilized around consistent performance benchmarks. This stabilization is critical for 2026 planners, as it reduces procurement uncertainty and allows for more precise forecasting of multi-year instrumentation programs.
Segmentation Architecture and Demand Vectors
Low frequency geophones are not a monolithic product category. Their performance specifications, deployment environments, and procurement cycles vary significantly across frequency bands, geographic markets, and application domains. Our research dissects these dimensions to reveal how demand is actually distributed across the industrial landscape, providing a practical lens for both suppliers and end-users.
The frequency spectrum segmentation highlights how different operational requirements drive distinct purchasing patterns. Instruments operating in the 1Hz to 2Hz range continue to anchor a substantial portion of market activity, reflecting their widespread utility in traditional seismic acquisition and structural analysis. The 2Hz to 4.5Hz band represents a complementary demand stream, often selected for applications requiring a balance between sensitivity and environmental robustness. Below 1Hz instruments, while occupying a smaller absolute share, are gaining strategic relevance in specialized scientific deployments, deep-earth imaging, and monitoring scenarios where extended low-frequency response is non-negotiable. Understanding how these bands interact with procurement cycles, lead times, and integration requirements is essential for organizations designing multi-sensor arrays or evaluating vendor capabilities.
Geographic distribution further shapes market dynamics. Demand flows are influenced by regional exploration activity, research funding patterns, and industrial infrastructure development. North American markets continue to exhibit strong procurement volumes, supported by established energy sector workflows and advanced geophysical research institutions. The Asia Pacific region demonstrates substantial and growing activity, driven by expanding mineral exploration programs, engineering monitoring initiatives, and domestic manufacturing capacity. European markets maintain a steady demand profile aligned with scientific research, environmental regulation compliance, and precision instrumentation standards. Meanwhile, the Middle East and Africa, as well as Latin America, reflect more targeted but strategically important demand pockets tied to resource exploration and regional seismic monitoring networks. The interplay between these regional flows creates a complex procurement environment where supply chain flexibility, localization strategies, and certification alignment increasingly determine competitive advantage.
Application-driven demand further diversifies the market landscape. Oil and gas exploration remains a foundational demand pillar, but its influence is being reshaped by evolving reservoir characterization techniques and the integration of low-frequency sensors into broader acquisition systems. Earthquake and seismology research continues to drive steady procurement, particularly as institutional funding supports long-term monitoring networks and hazard assessment programs. Structural health monitoring represents a growing industrial application, where low frequency sensing is increasingly embedded into infrastructure safety protocols and predictive maintenance frameworks. Mining and mineral exploration adds another layer of demand, with operators leveraging improved low-frequency response to enhance subsurface resolution in complex geological settings. Each application vector carries distinct performance expectations, volume profiles, and replacement cycles, making application-level intelligence a critical input for both product strategy and sales planning.
Competitive Landscape and Strategic Positioning
The worldwide low frequency geophone market is characterized by a mix of established instrument manufacturers, specialized sensor providers, and regional equipment suppliers. Market concentration data indicates that the top three players collectively account for approximately 48.5 percent of revenue, while the top five firms extend their share to roughly 62.3 percent. This concentration pattern suggests a market where incumbency, technical certification, and integration capability matter significantly, but where mid-tier and regional players retain meaningful opportunities through customization, cost structure, and application-specific support.
Several companies define the current competitive architecture. Geospace Technologies Corporation, headquartered in Houston, Texas, maintains a prominent position through its portfolio of low-frequency seismometers and related sensors, including the GS-ONE LF, GS-1, and HS-1 models. Its product lineup is engineered for seismic exploration, structural analysis, geologic hazard assessment, and carbon storage monitoring, reflecting the broadening application base that defines the modern market. Sercel, based in Carquefou, France, brings a strong heritage in very low-frequency and long-period signal capture, with offerings such as the L-4 and L-22 seismometers and the SG-5 high-sensitivity sensor. Its emphasis on scientific studies, geophysical research, and oil and gas exploration underscores the crossover between academic-grade precision and industrial deployment.
In China, Seis Tech supplies very low frequency geophones, including 1Hz vertical and horizontal models, alongside high-sensitivity and triaxial variants. Its coverage spans petroleum and gas, mining, engineering, and passive seismic or earthquake monitoring, illustrating how regional manufacturers are expanding into both traditional and emerging application domains. Zhaofeng Sensor Equipment Co Ltd, also known as ZFGEO and based in Baoding City, manufactures and customizes high and low frequency geophone sensors, including 2Hz and 3Hz models, for oil and gas, mineral, and geotechnical exploration, with products tested across more than 65 countries. This international validation footprint is a meaningful differentiator in markets where field reliability and cross-border deployment experience influence procurement decisions.
Additional players contribute to a diverse supply ecosystem. Cable and Supplies, Inc., operating in the USA, provides low frequency geophones such as the 1Hz PS-1 seismometer and the 2Hz PS-2/260 and PS-2B models, alongside 2.5Hz and 2.7Hz velocity sensors. INOVA Geophysical focuses on precision seismic sensors, including the SN5A-5 high-sensitivity geophone designed for nodal and cable systems. Kinemetrics, Inc. supplies seismic sensors for monitoring and exploration applications, while Nanometrics, based in Canada, delivers high-precision geophones and seismometers for research and industrial low frequency use. Geometrics, also USA-based, offers seismographs with low frequency options extending down to 0.6Hz or DC, integrated with geophone systems for exploration workflows. PASI SRL, in Italy, manufactures geophones across various frequencies, including low frequency models such as 2Hz units for geophysical surveys.
Recent strategic movements highlight how competition is evolving beyond product catalogs. In July 2024, Geospace Technologies launched the GS-LF-X low-frequency geophone model targeting both marine seismic and onshore exploration applications, signaling a deliberate push into broader deployment environments. In April 2024, Geometrics announced a strategic partnership with Sensor Networks to integrate rugged, remote-deployed low-frequency geophones into distributed sensing arrays. This type of collaboration reflects a market trend where sensor performance is increasingly evaluated as part of a larger system architecture, rather than as a standalone component.
Industry Dynamics: Materials, Compliance, and Macro-Driven Demand
The operational reality of low frequency geophone manufacturing and deployment is shaped by a set of technical, regulatory, and macroeconomic forces that directly affect sourcing, qualification, and long-term reliability. At the component level, these instruments depend heavily on precision electromagnetic coils, magnets, and springs. Manufacturing processes must maintain frequency tolerance under tilt and temperature variations, which places a premium on material selection, assembly control, and quality assurance. For procurement teams, this means that supplier capability is not simply a matter of unit cost; it is tied to engineering rigor, tolerance consistency, and the ability to reproduce performance across production runs.
Worldwide Low Frequency Geophone Market
Worldwide Hydrophone Market
Regulatory and standards compliance further frames the competitive environment. Major suppliers maintain certifications such as ISO 9001:2015 for quality management, ISO 14001:2015 for environmental management, and ISO 45001:2018 for occupational health and safety. These certifications are more than administrative markers. They signal operational discipline, reduce qualification risk for large-scale procurement programs, and often serve as prerequisites for partnerships with government-funded research initiatives or regulated industrial projects. In markets where contract awards depend on documented process control and supply chain transparency, compliance readiness can be a decisive factor.
Macro trends are also reshaping demand fundamentals. The push toward carbon storage monitoring, induced seismicity tracking for CCS projects, and deep seismic exploration requiring extended low-frequency response is expanding the addressable use case pool beyond traditional exploration workflows. Low frequency geophones in the 1Hz to 5Hz range are increasingly viewed as enabling instruments for verification, monitoring, and risk management in projects where subsurface behavior must be observed over long time horizons. This shift has practical implications for product planning, service contracts, and deployment models, as end-users seek sensors that can support continuous or semi-continuous monitoring rather than one-time acquisition campaigns.
Strategic Value for 2026 Decision-Making
The 2026 decision environment demands more than high-level market awareness. Leaders need actionable intelligence that connects market size and growth rates to procurement timing, vendor evaluation, application planning, and risk management. This research study is structured to support that need by translating macro trends into operational context.
For technology and procurement leaders, the report provides a structured view of how frequency bands, application requirements, and regional demand patterns intersect. This helps organizations avoid over-indexing on a single segment or misreading the balance between exploration-driven and monitoring-driven procurement. For product and business development teams, the competitive landscape analysis offers a baseline for positioning, differentiation, and partnership strategy, especially as system-level integration and remote deployment become more prominent evaluation criteria. For executive planning, the forecast trajectory and concentration data provide a reality check on market maturity, competitive intensity, and the realistic scope for share capture in a market where incumbency and certification matter.
Equally important, the study frames the market in terms of transition risk and opportunity. Organizations that rely on low frequency geophones for conventional exploration must account for the growing relevance of environmental monitoring, carbon storage verification, and induced seismicity tracking. Suppliers and integrators that recognize this expansion can align product roadmaps, service offerings, and deployment models with the next wave of demand. Buyers who understand these dynamics can structure multi-year procurement with greater confidence, balancing cost efficiency against performance requirements and future-proofing their sensor networks.
What the Full Report Delivers
This introduction is designed to demonstrate the depth and applicability of the study while preserving the detailed segmentation, company-level benchmarking, and forecast breakdowns for the full report. The complete Worldwide Low Frequency Geophone Market research delivers a fully integrated view of the market across historical performance, segmentation splits, competitive profiles, and forward forecasts. It includes:
- A comprehensive revenue trajectory spanning the 2020 to 2025 historical period and the 2026 to 2032 forecast window, expressed in USD million, with a 7.0 percent CAGR framework that clarifies the pace and shape of market expansion.
- Detailed segmentation analysis across region, type, and application, enabling readers to understand how demand is distributed and where strategic focus may yield the strongest returns.
- In-depth company profiles for leading manufacturers and sensor providers, including headquarters location, product capabilities, and application coverage, along with recent developments that illustrate how the competitive field is evolving.
- Contextual analysis of industry dynamics, including component-level manufacturing considerations, compliance and certification patterns, and macro-driven demand shifts tied to carbon storage monitoring, induced seismicity tracking, and deep seismic exploration.
- Practical guidance for interpreting market concentration, evaluating supplier qualification criteria, and aligning procurement or product strategy with the shifting mix of exploration, research, monitoring, and industrial applications.
The full report is intended to serve as a working intelligence asset rather than a static overview. It is built to support scenario planning, vendor assessment, market entry evaluation, and strategic forecasting in a sector where technical performance, regulatory readiness, and application expansion are increasingly intertwined.
Conclusion
The worldwide low frequency geophone market is moving through a period of structural expansion, application diversification, and system-level integration. Historical growth has established a solid revenue base, while the forecast period points to continued momentum shaped by both traditional exploration needs and emerging monitoring responsibilities. For organizations operating in 2026, the strategic question is no longer whether this market matters, but how to interpret its segmentation, competitive concentration, and demand drivers with enough precision to act confidently.
This research study provides that interpretive framework. It connects market size, growth trajectory, segmentation logic, and competitive activity into a coherent decision-support structure, while leaving the granular breakdowns and detailed benchmarking for the complete report. For executives and analysts who need a reliable foundation for 2026 planning, the full study offers the depth required to move from market awareness to informed action.
For detailed analysis of this topic, please visit the official page: Worldwide Low Frequency Geophone Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Garlic Supplements Market Hits $745.50M in 2025, Projects 5.95% CAGR to $1,117.27M by 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Next Growth Cycle: Inside the Worldwide Garlic Supplements Market (2026–2032)
The global dietary supplement sector continues to mature, shifting from broad wellness claims toward targeted, evidence-backed formulations. Within this landscape, garlic-derived products have carved out a distinctive position by bridging cardiovascular care, immune resilience, and digestive support with a consumer base that increasingly demands potency, purity, and transparency. Our newly released Worldwide Garlic Supplements Market research study provides a structured, forward-looking view of this category, mapping the trajectory from 2026 through 2032 and equipping leadership teams with the intelligence needed to allocate resources, position portfolios, and anticipate inflection points.
For executives navigating category expansion, supply chain volatility, or clinical positioning, this report functions as a decision-ready reference. Rather than offering a static snapshot, it frames the market as a dynamic system shaped by formulation innovation, raw material sourcing, regulatory expectations, and evolving consumer health priorities. The analysis is built to support scenario planning, not just retrospective reporting.
Market Trajectory and Forecasting Framework
The study establishes a clear baseline from historical performance between 2020 and 2025, then extends into a detailed forecast window covering 2026 to 2032. This dual lens allows readers to trace how recent adoption patterns, distribution expansion, and product innovation have set the stage for the next growth phase. The forecast reflects a measured but sustained expansion path, anchored by a five-year compound annual growth rate of 5.95 percent. Revenue projections are presented in U.S. dollars, with figures scaled in millions to support regional planning, budgeting, and investment prioritization.
At the close of the most recent historical year, total market value reached approximately $745.5 million. The forecast model projects a continued step-up in annual revenue, moving from $789.86 million in 2026 to $836.86 million in 2027, $886.65 million in 2028, and $939.4 million in 2029. The trajectory continues upward through 2030 at $995.3 million, 2031 at $1,054.52 million, and 2032 at $1,117.27 million. This progression signals more than incremental growth; it reflects a structural shift in how garlic-based supplements are positioned across mainstream wellness, specialty nutrition, and condition-focused formulations.
Importantly, these figures are presented within a broader analytical architecture. The report connects top-line sizing with underlying demand drivers, consumer behavior shifts, and category mechanics so that leadership teams can interpret revenue growth in context. Readers gain visibility into where momentum is building, which segments are accelerating, and how forecast assumptions align with observable industry signals.
Worldwide Garlic Supplements Market
Category Architecture and Product Form Dynamics
Garlic supplements are no longer evaluated solely on basic garlic content. Formulation strategy now differentiates brands by bioavailability, taste mitigation, dosage convenience, and compatibility with broader wellness routines. The report examines the category through a form-based lens, assessing how capsules, tablets, softgels, and powder or liquid formats each serve distinct usage occasions and consumer expectations.
Capsules remain a core vehicle for standardized dosing and clean-label positioning. Tablets continue to appeal to consumers prioritizing convenience and shelf stability. Softgels occupy a notable share of the premium convenience segment, often favored for smoother ingestion and perceived potency delivery. Powder and liquid formats are increasingly explored for functional integration, targeted blends, and specialty use cases, though they typically serve more niche demand profiles.
Rather than presenting fragmented percentages, the analysis focuses on how these form preferences interact with purchasing behavior, retail placement, and formulation economics. The study explores how products optimized for odor control, enteric protection, cold-processing, or aged extraction are influencing repeat purchase behavior and brand trust. It also examines how format decisions affect packaging, cost structure, and channel strategy, helping brands align product architecture with target customer profiles.
Application Landscape and Health-Focused Positioning
The demand side of the garlic supplements market is shaped by a set of converging health priorities. Cardiovascular support remains a central driver, reflecting sustained consumer interest in circulation, arterial function, and heart-healthy routines. Immune system support has also become an anchor for category relevance, particularly as consumers seek everyday wellness products with botanical and functional ingredients. Digestive health represents a third application pillar, with garlic formulations positioned around broader gastrointestinal and systemic wellness narratives. Additional application areas extend the category into wider health maintenance and targeted lifestyle support.
The report evaluates these application pathways not as isolated silos, but as overlapping demand streams that influence messaging, ingredient disclosure, and clinical positioning. For example, cardiovascular-oriented products often emphasize standardized potency and extraction quality, while immune- and digestive-focused offerings may highlight daily-use convenience and compatibility with broader supplement regimens. By mapping application demand against product attributes and channel mechanics, the study helps brands determine where to compete on efficacy, where to lead with convenience, and where to differentiate through ingredient storytelling.
Regional Demand Patterns and Market Concentration
Geographically, the market displays differentiated demand profiles shaped by consumer awareness, retail infrastructure, supplementation culture, and distribution maturity. North America continues to represent a substantial demand center, supported by established supplement purchasing habits and broad retail and e-commerce coverage. Europe reflects a mature wellness environment with strong interest in botanical ingredients and condition-adjacent formulations. Asia Pacific stands out for its expanding consumer base and growing integration of traditional plant-based ingredients into modern supplement formats. Rest of World markets contribute additional growth potential, though with more varied access dynamics and channel development stages.
Rather than reducing the regional picture to isolated figures, the report uses geographic analysis to explain how local purchasing behavior, regulatory expectations, and distribution reach shape market opportunities. This approach enables leadership teams to evaluate where to prioritize supply commitments, where to test new formats, and where to adapt messaging to regional health norms.
On the competitive side, the market remains moderately fragmented. The top three players collectively account for 18.55 percent of market share, while the top five reach 26.42 percent. This concentration pattern suggests that brand positioning, formulation credibility, and channel relationships still leave meaningful room for differentiated entrants, especially those with clear clinical narratives, distinctive extraction methods, or strong value propositions in priority sub-segments.
Competitive Landscape and Leading Participant Profiles
The study profiles the companies shaping category standards, distribution pace, and consumer trust. These participants illustrate the strategic diversity within the market, ranging from clinically oriented extract specialists to broad-spectrum wellness brands and value-focused format leaders.
Nature's Bounty, headquartered in Bohemia, New York, has developed a recognizable line of odorless garlic softgels and tablets positioned around heart and circulatory support. Its product architecture emphasizes dosage clarity and odor-minimizing techniques such as cold-processing or enteric coating, addressing a common barrier to consistent garlic supplement use. Wakunaga of America, known through its Kyolic brand in Mission Viejo, California, takes a different approach by specializing in Aged Garlic Extract. The company emphasizes its proprietary aging process and backs its cardiovascular, immune, and circulation claims with a substantial clinical library. Its formula range, including Formula 100, 105, 106, and Reserve, reflects a strategy centered on standardization, tolerability, and scientific credibility.
NOW Foods, based in Bloomingdale, Illinois, positions garlic oil softgels and odorless garlic concentrate capsules as practical wellness options, often framed as equivalent to whole garlic cloves for general health maintenance. Swanson Health Products, operating out of Fargo, North Dakota, combines Kyolic aged garlic extract offerings with its own odorless garlic capsules, targeting both cardiovascular and immune function within a value-conscious retail environment. Gaia Herbs, located in Brevard, North Carolina, integrates garlic supplements into a broader herbal and spice supplement portfolio, reinforcing a natural, quality-focused brand narrative. Nature's Way, from Green Bay, Wisconsin, includes garlic-based products in its wide herbal portfolio, appealing to consumers seeking general health support within a trusted botanical brand framework.
Doctor's Best, based in Garden Grove, California, places garlic extract options within a science-oriented supplement lineup, while Jarrow Formulas, from Los Angeles, focuses on standardized garlic extracts with an emphasis on cardiovascular health. Solgar, headquartered in Leonia, New Jersey, markets garlic capsules as part of a premium vitamin and herbal supplement presentation, targeting consumers who associate quality packaging and formulation discipline with higher-tier wellness products. Puritan's Pride, based in Holbrook, New York, competes partly on accessibility and value, offering garlic softgels and tablets with a clear heart health focus.
This competitive mix matters because category leadership is increasingly defined by formulation discipline, evidence alignment, and consumer trust rather than price alone. The report examines how these companies position across quality tiers, format preferences, and application narratives, helping readers identify which strategic models are scaling and which gaps remain open for targeted entry.
Recent Innovation Signals and Industry Context
Market intelligence is most useful when paired with current developments that change how brands should think about claims, formulation, and demand. One notable development in early 2025 centered on Kyolic aged garlic extract, with a clinical trial published in February 2025 showing that daily supplementation with 1.2 to 2.4 grams of aged garlic extract powder over 12 weeks was associated with improved aerobic fitness markers, including VO2 max and lactate threshold, faster recovery times, enhanced arterial flexibility, and reduced cardiovascular risk proteomic biomarkers in middle-aged recreational endurance athletes. While individual studies do not define a category on their own, they illustrate how clinical attention is expanding beyond basic heart health toward performance recovery, vascular function, and biomarker-level outcomes.
This type of evidence trajectory influences brand positioning in practical ways. It supports more nuanced messaging around circulation, endurance, and vascular support, but it also raises expectations for transparency, extract standardization, and dosage consistency. The report places these developments in context, helping companies assess how clinical signals can strengthen or complicate market positioning depending on formulation integrity and claim discipline.
Beyond clinical activity, the study incorporates operational and regulatory realities that directly affect category execution. Dietary supplements, including garlic products, are regulated as foods rather than drugs under FDA oversight. This framework requires adherence to current good manufacturing practices but does not involve pre-market approval for efficacy claims. For brand leaders, that means competitive advantage increasingly depends on manufacturing quality, label clarity, and claim support rather than on regulatory gatekeeping.
Raw material sourcing introduces another layer of strategic importance. Garlic supplements primarily rely on garlic bulb extracts or aged garlic extract derived from Allium sativum, with major cultivation concentrated in regions such as China, India, and the United States. This sourcing geography shapes supply availability, cost exposure, and quality consistency, making supply chain planning and extraction control essential components of market readiness. At the same time, food safety events in adjacent garlic product channels underscore the importance of temperature control, handling discipline, and recall readiness. A recalled peeled garlic segment in the broader fresh garlic market highlighted the operational risks that can arise when storage conditions are not properly managed. Although such events occur in adjacent product categories, they reinforce the broader industry expectation that quality assurance, traceability, and safety protocols are central to consumer trust in any garlic-based offering.
What the Report Delivers for Strategic Decision-Making
The Worldwide Garlic Supplements Market study is structured to support concrete business decisions rather than general market awareness. It brings together sizing, segmentation, competitive profiling, application dynamics, and regulatory context into a single decision framework. Readers can use the report to:
- Evaluate forecast trajectories and base planning assumptions on a structured 2026–2032 outlook.
- Understand how product form, application focus, and regional demand interact to shape growth opportunities.
- Compare competitive positioning models across premium, science-backed, value-oriented, and herbal-narrative strategies.
- Assess formulation and sourcing considerations that influence cost, quality, and shelf positioning.
- Identify where clinical evidence, extraction quality, and odor-control technology create differentiation.
- Prepare for regulatory and food-safety expectations that shape manufacturing, labeling, and consumer confidence.
The analysis also provides a clear map of where fragmentation remains, where concentration is increasing, and where brand entry or expansion can be most effectively timed. By linking market structure to commercial execution, the report helps teams move from curiosity to action.
Why This Study Matters for 2026 Planning
In a category where demand is expanding but competition is becoming more refined, general trend awareness is not enough. Leadership teams need to understand how forecast momentum translates into segment opportunity, how product architecture affects repeat purchase behavior, and how competitive differentiation is increasingly tied to extract quality, clinical framing, and manufacturing credibility. The report is designed to support those decisions with coherent analysis and actionable structure.
More importantly, it helps organizations avoid decisions built on incomplete comparisons or surface-level category assumptions. Whether the objective is to launch a new garlic supplement line, reposition an existing brand, enter a priority geography, or benchmark a competitive set, the study provides the context needed to evaluate trade-offs with greater confidence.
Worldwide Brewer Yeast Supplements Market
The full research package contains the detailed segmentation breakdowns, company profiles, regional demand analysis, forecast tables, and competitive assessment needed to support planning, investment review, and portfolio strategy. To access the complete dataset and proprietary market view, request the full report through the source page and explore the full depth of the Worldwide Garlic Supplements Market intelligence.
For detailed analysis of this topic, please visit the official page: Worldwide Garlic Supplements Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Hypersomnia Drug Market Hits $5.0B in 2025, Forecasted to Reach $10.06B by 2032 at 10.5% CAGR
By pmarketresearch, 2026-09-16
Strategic Imperatives in the Worldwide Hypersomnia Drug Market: A 2026 Decision-Maker's Guide
The landscape of central nervous system therapeutics is undergoing a profound transformation, driven by heightened clinical recognition of hypersomnia disorders and a shifting competitive environment. As we navigate the forecast period from 2026 through 2032, the Worldwide Hypersomnia Drug Market represents a critical frontier for pharmaceutical strategy, investment capital, and healthcare access initiatives. Our latest comprehensive market research serves as an essential compass for executives aiming to navigate the complexities of this high-growth therapeutic area.
This article outlines the strategic context surrounding the hypersomnia market, synthesizing macroeconomic trajectories, competitive maneuvers, and regulatory dynamics. It is designed to demonstrate the depth of intelligence available in our full study, providing decision-makers with the context needed to appreciate the value of detailed segmentation and forward-looking analysis.
Worldwide Sedative-Hypnotic Drug Market
Macroeconomic Trajectory and Growth Catalysts
The hypersomnia drug market has demonstrated robust resilience and expansion over the historical period from 2020 to 2025. Analysis of revenue data reveals a consistent upward trend, with total market revenues climbing from approximately 3.1 billion USD in 2020 to over 5 billion USD in 2025. This historical performance underscores the increasing prevalence of diagnosed conditions such as narcolepsy and idiopathic hypersomnia, coupled with improved treatment adherence and diagnostic capabilities.
Looking ahead, the forecast period from 2026 to 2032 projects continued momentum. The market is expected to accelerate toward the 10 billion USD threshold by 2032. This growth is underpinned by a Compound Annual Growth Rate (CAGR) of 10.5 percent. Such a trajectory indicates more than mere population growth; it reflects a dynamic ecosystem where innovation in drug delivery, new chemical entities, and expanding indications are converging to broaden the total addressable market. However, realizing the full potential of this forecast requires nuanced understanding of regional variances, drug class utilization, and the impact of generic competition, all of which are detailed in our full report.
Thematic Forces Reshaping Market Dynamics
Several structural forces are redefining the competitive playbook for hypersomnia therapeutics. Understanding these dynamics is vital for strategic positioning in 2026 and beyond.
Worldwide Hypersomnia Drug Market
- Regulatory Complexity and Access Constraints : The classification of key oxybate therapies, such as sodium oxybate, under Schedule III controlled substances necessitates rigorous risk evaluation and mitigation strategies. The REMS program imposes specific distribution and handling requirements that influence prescribing patterns, reimbursement negotiations, and patient access logistics. Strategic planners must account for how these regulatory frameworks impact market penetration rates and commercial infrastructure requirements.
- Sodium Content and Formulation Innovation : A significant differentiator in the oxybate class is sodium content. Formulations with reduced sodium profiles offer distinct clinical advantages for patients with comorbidities related to cardiovascular health or dietary restrictions. The availability of mixed oxybate salts with significantly lower sodium content compared to traditional sodium oxybate has expanded the treatment landscape. This innovation not only addresses specific patient needs but also influences formulary positioning and prescriber preference, particularly where long-term safety profiles are scrutinized.
- Generic and Authorized Generic Entry : The erosion of exclusivity barriers for certain oxybate products has introduced pricing pressure and alternative access pathways. The emergence of authorized generics and ANDA-approved sodium oxybate oral solutions provides payers and healthcare systems with more affordable options for narcolepsy and related hypersomnia symptoms. This shift alters the competitive intensity within the branded segment and necessitates robust lifetime value modeling for innovators, while simultaneously creating opportunities for generic manufacturers to capture volume.
- Pipeline Diversification and Mechanism of Action : Beyond oxybates and traditional stimulants, the pipeline is rich with novel mechanisms. Histamine-3 receptor antagonists and orexin receptor agonists represent transformative approaches to wake promotion. The development of oral selective orexin 2 receptor agonists, in particular, marks a potential paradigm shift, offering non-scheduled alternatives with differentiated efficacy profiles. These candidates are advancing through clinical stages and attracting significant corporate interest, signaling a broadening of the therapeutic arsenal.
Competitive Landscape: Incumbents and Challengers
The competitive architecture of the hypersomnia market is characterized by a concentration of key players holding significant market share, alongside a wave of agile entrants and pipeline developers seeking to disrupt established norms. Our analysis identifies a core group of companies that are driving value creation and reshaping therapeutic standards.
Jazz Pharmaceuticals remains a dominant force, anchored by its portfolio of oxybate-based therapies. Its leadership is reinforced by the possession of FDA-approved treatments specifically indicated for idiopathic hypersomnia in adults, alongside therapies for narcolepsy. This dual-indication capability positions the company at the intersection of the two largest symptom clusters within the hypersomnia spectrum. The strategic focus on differentiated formulations and patient support programs continues to drive brand loyalty and market share retention.
Avadel Pharmaceuticals is executing a pivotal strategy centered on extended-release oxybate technology. With the completion of patient enrollment in a Phase 3 trial evaluating its extended-release sodium oxybate for idiopathic hypersomnia, the company is poised to potentially expand its label and capture additional patient populations. The anticipated data readout in the near term represents a binary event that could significantly alter the company's valuation and market positioning. Meanwhile, its commercialized product for narcolepsy provides a revenue base and operational foothold in the CNS space.
Harmony Biosciences and Bioprojet Pharma are leveraging the histamine-3 receptor antagonist mechanism. Pitolisant, as a non-stimulant wake-promoting agent, offers a distinct safety and tolerability profile compared to traditional stimulants. Its utility in managing excessive daytime sleepiness associated with narcolepsy and its potential application in broader hypersomnia symptom management make it a versatile asset in the treatment algorithm. As awareness of non-stimulant options grows, these companies are well-positioned to capture share among patients and providers seeking alternatives to controlled substances.
Teva and Amneal are central to the generic and volume-driven segment. Teva's supply of generic wake-promoting agents, including modafinil and armodafinil, ensures broad accessibility for off-label and approved uses related to excessive daytime sleepiness. Amneal's recent regulatory milestones, including approval for sodium oxybate oral solution referencing a branded product, highlight the intensifying competition in the oxybate space. These entries expand the availability of lower-cost alternatives, influencing pricing dynamics and access strategies across the market.
Alkermes, Inc. is pursuing a high-risk, high-reward strategy with its oral selective orexin 2 receptor agonist. The receipt of FDA Breakthrough Therapy Designation for narcolepsy type 1 underscores the clinical promise of this mechanism. With development activities extending to idiopathic hypersomnia, Alkermes is targeting a potential best-in-class profile that could redefine treatment standards if clinical and regulatory milestones are met successfully.
Takeda Pharmaceutical continues to advance its orexin receptor agonist pipeline, including multiple candidates in clinical development. As a global pharmaceutical giant, Takeda's involvement signals the strategic importance of the orexin pathway and brings substantial resources to the race for novel mechanisms. The progress of these candidates contributes to the overall optimism surrounding the future of hypersomnia treatment.
Tris Pharma has achieved regulatory traction with the FDA acceptance of its NDA for a once-nightly low-sodium oxybate formulation. This filing covers both narcolepsy and idiopathic hypersomnia indications, positioning the product to address a broad patient base with a convenient dosing regimen. The upcoming regulatory decision window represents a key catalyst for the company and a potential new entry point for competitive pressure in the oxybate category.
Zevra Therapeutics and other CNS-focused entities are also active participants, contributing to the diversity of approaches and the overall vibrancy of the innovation ecosystem. Their presence underscores the interest in idiopathic hypersomnia as a distinct therapeutic area with unmet needs that warrant dedicated development efforts.
Recent Corporate Activity and Market Signals
Recent M&A and clinical developments provide real-time indicators of market confidence and strategic priorities. The pharmaceutical industry's willingness to deploy significant capital in this space is evident. For instance, a major acquisition agreement involving a large-cap pharmaceutical company and a biotech firm with an orexin receptor 2 agonist pipeline highlights the premium placed on novel mechanisms targeting narcolepsy and idiopathic hypersomnia. Such transactions signal to the market that orexin-based therapies are viewed as high-value assets capable of commanding substantial returns, thereby encouraging further investment in related R&D programs.
Additionally, the completion of patient enrollment in pivotal trials, such as the Phase 3 study for extended-release sodium oxybate in idiopathic hypersomnia, removes a key execution risk for developers. The proximity of data readouts creates anticipation and potential volatility, requiring stakeholders to monitor these events closely as they may trigger shifts in market share expectations and competitive responses.
Regulatory filings and approvals continue to reshape the supply side. The acceptance of NDAs for once-nightly formulations and the approval of generic oxybate products reflect an environment of both innovation and commoditization occurring simultaneously. Companies must balance the opportunities presented by new indications and formulations against the realities of increasing competition and access pressures from lower-cost alternatives.
Strategic Questions for 2026 Decision-Makers
As organizations formulate their strategies for the current fiscal year and the ensuing forecast horizon, several critical questions demand answers that go beyond surface-level metrics:
- How will the interplay between branded differentiation and generic pressure evolve across different drug classes, and what pricing and contracting strategies are required to protect value?
- Which clinical and regulatory milestones in the orexin and histamine pathways will serve as inflection points for treatment algorithms, and how should commercial teams prepare for rapid adoption scenarios?
- How do regional reimbursement landscapes and access restrictions influence the relative attractiveness of specific indications and formulations, and where are the hidden pockets of growth?
- What is the realistic impact of sodium-reduction trends and once-nightly dosing convenience on patient adherence and market penetration, and how should this inform product development and marketing messaging?
- How should companies benchmark their positioning against the high concentration of market share held by leading incumbents, and what partnership or acquisition opportunities exist to accelerate pipeline progress?
Conclusion: The Value of Granular Intelligence
The Worldwide Hypersomnia Drug Market stands at a juncture of significant opportunity, driven by robust growth projections, a deepening therapeutic arsenal, and dynamic competitive interactions. A CAGR of 10.5 percent and a projected expansion toward the 10 billion USD mark by 2032 confirm the sector's status as a priority area for strategic investment. However, navigating this market successfully requires more than aggregate data. It demands a granular understanding of segmentation nuances, competitive positioning, regulatory tailwinds and headwinds, and the specific value drivers that differentiate one therapy from another.
Our comprehensive market research report delivers the precision intelligence required to act on these insights. From detailed segmentation analysis across regions, drug classes, and indications to deep-dive company profiles and scenario-based forecasting, the study equips stakeholders with the tools to make informed, confident decisions. To access the full spectrum of data, including precise market sizing for each segment, competitive share breakdowns, and actionable strategic recommendations, we invite you to explore the complete report.
Unlock the full intelligence behind the hypersomnia market's trajectory and secure your strategic advantage for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Hypersomnia Drug Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aluminum Exhibits Market Hits $4,210M in 2025, Projected to Reach $7,088.63M by 2032 at 7.73% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Aluminum Exhibits Market: Navigating Growth and Complexity in 2026
The global aluminum exhibits market stands at a pivotal inflection point. As organizations across trade shows, events, and retail environments demand more modular, sustainable, and technologically integrated display solutions, the strategic importance of precise market intelligence has never been higher. This article serves as a preview of our latest comprehensive market research report, designed to equip executives, investors, and supply chain leaders with the contextual depth needed to make informed decisions throughout 2026 and beyond.
The underlying market dynamics reflect both robust expansion and intensifying structural complexity. Historical performance from 2020 to 2025 demonstrates a trajectory shaped by post-pandemic event recovery, accelerated adoption of lightweight aluminum frameworks, and the rapid digitalization of physical exhibition spaces. Looking forward, our forecast period spanning 2026 through 2032 maps a continued growth pathway underpinned by predictable demand drivers, though one that is simultaneously tested by raw material volatility, shifting trade regulations, and evolving competitive positioning. Understanding where the market is headed, and why, requires moving beyond headline numbers into the operational and strategic layers that actually drive commercial outcomes.
Macro Trajectory and the 2026 Decision Window
The market has expanded materially over the past half-decade, scaling from approximately 1,650 million USD in 2020 to an estimated 4,210 million USD by 2025. That progression reflects more than a simple rebound; it signals a structural recalibration in how exhibitors, event producers, and brand managers approach physical environments. Aluminum's inherent advantages, recyclability, modularity, strength-to-weight ratio, and compatibility with integrated lighting and digital media, have cemented its role as a foundational material in modern exhibit design.
Our forecast model projects the market to reach 4,426.72 million USD in 2026, with growth compounding at a 7.73 percent CAGR through the end of the forecast window. By 2032, the market is positioned to approach the 7,088.63 million USD threshold. These are not abstract projections. They represent a demand environment in which procurement teams must plan for capacity, pricing, and supply continuity; in which manufacturers must decide where to allocate R&D and production resources; and in which investors must distinguish between cyclical noise and durable secular growth.
The 2026 decision window is particularly consequential because multiple forces are converging simultaneously. Demand for reconfigurable and reusable exhibit packages continues to rise as organizations seek to reduce waste, lower total cost of ownership, and maintain brand consistency across multiple event locations. At the same time, the cost and availability of aluminum as a primary input have become critical variables in margin management and pricing strategy. Leaders who treat 2026 as a planning anchor rather than a reactive operating year will be better positioned to capture share while managing downside risk.
Structural Shifts Across Product Types and Applications
The market's growth is not uniform across all product types or end-use applications. Instead, it is being reshaped by clear preference patterns that favor flexibility, speed of deployment, and design precision. Modular systems, which enable rapid assembly, reconfiguration, and reuse across different event footprints, have captured a substantial share of commercial activity. Their appeal lies in their ability to reduce labor costs, shorten setup timelines, and support sustainability objectives by extending the usable life of exhibit assets.
Truss systems continue to serve a distinct but meaningful role, particularly where structural spans, overhead installations, and architectural visibility are priorities. Custom extrusions, meanwhile, cater to organizations that require highly tailored geometries, integrated functional elements, or specialized finishes that standard configurations cannot deliver. Together, these categories illustrate a market that is simultaneously standardizing at the modular level while still rewarding engineering-driven customization where brand differentiation or functional requirements demand it.
Application-side dynamics reinforce this divergence. Trade shows and exhibitions remain the dominant commercial engine, reflecting the ongoing centrality of in-person industry gatherings, product launches, and brand immersion experiences. Events and concerts contribute a notable secondary demand stream, particularly where temporary stage architectures, scenic structures, and branded environments rely on aluminum's portability and load-bearing capabilities. Retail and interior displays represent a growing adjacency, as brands extend exhibit-grade modular logic into permanent or semi-permanent storefront environments, pop-up retail, and experiential showrooms.
What matters for strategic planning is not simply which category is largest, but how these segments interact. Modular platforms increasingly serve as the backbone for multi-application deployments. A single engineered frame may support a trade show booth in one quarter, a concert staging element in another, and a retail display installation thereafter. This cross-application flexibility changes the economics of product development and procurement, placing a premium on systems that can adapt without sacrificing structural integrity or aesthetic consistency.
Aluminum Exhibits Market
Competitive Landscape and the Battle for Differentiation
The competitive environment reflects a blend of established manufacturers, specialized engineering firms, and extrusion specialists, many of which are pursuing differentiation through design capability, material innovation, and technology integration. Several companies have defined themselves through a clear strategic identity rather than competing solely on price.
Aluvision has positioned itself at the intersection of modular aluminum framing and immersive brand environments, with an emphasis on sustainable design and LED-integrated solutions. Its trajectory illustrates how exhibit manufacturers are increasingly expected to deliver more than structural components; they are being asked to support lighting, media integration, and environmentally responsible production practices within a single system.
Agam brings more than four decades of experience in engineered modular aluminum structures and extrusions, serving exhibit companies and agencies that require reliability, repeatability, and technical depth. Its recent industry analysis emphasizes a market-wide shift toward smarter and more efficient modular builds, signaling that performance optimization and material efficiency are becoming core purchasing criteria rather than secondary considerations.
Skyline Exhibits continues to operate across the full spectrum of custom modular trade show exhibits and displays, combining design, manufacturing, and management services with fast-ship kits and full-service deployment options. Its recognition in the 2026 MUSE Creative Awards underscores how creative execution and engineering discipline are increasingly evaluated together by buyers who view exhibits as both functional infrastructure and brand communication tools.
The broader supplier ecosystem includes organizations such as Exhibit and Display Truss, Abex, Extrude-A-Trim, 80/20 Inc., and Nova Display, each contributing distinct capabilities ranging from aluminum truss structures and lightweight reconfigurable booths to T-slot extrusion systems and modular floor stands or showcases. The presence of multiple specialized players indicates a market that rewards technical versatility and responsive service, especially for customers managing tight event schedules or complex installation constraints.
From a concentration standpoint, the market remains moderately fragmented, with the top three players accounting for roughly 32.4 percent of revenue and the top five approaching 45.6 percent. This structure suggests that while scale players hold meaningful influence, there is still substantial room for mid-sized and specialized firms to compete on engineering quality, regional responsiveness, customization depth, and integration capabilities. For procurement leaders, this fragmentation is strategically useful: it supports negotiation leverage, encourages supplier diversification, and allows organizations to match specific vendors to specific project requirements rather than relying on a single universal source.
External Pressures: Materials, Trade Policy, and Supply Dynamics
No strategic assessment of the aluminum exhibits market in 2026 would be complete without confronting the external forces that directly shape cost structures and supply availability. Raw material prices have become a central boardroom topic, and aluminum is no exception. Recent market conditions show aluminum prices moving higher through early 2026, with cash prices climbing above the 3,000 USD per tonne level and extending further as supply concerns and trade policy effects interacted with demand. By mid-May 2026, LME aluminum cash pricing reached approximately 3,564 USD per tonne, a notable year-over-year increase that underscores the importance of monitoring input costs at a granular level.
This pricing environment has direct implications for manufacturers, fabricators, and exhibit buyers. For producers, it reinforces the need for forward sourcing strategies, hedged procurement where appropriate, and design choices that optimize material yield. For exhibit purchasers, it highlights the value of reusable and modular systems that reduce repeated material exposure across multiple events. In practical terms, the organizations that succeed in this environment are those that treat aluminum cost not as a static line item, but as a variable to be managed through product architecture, inventory planning, and supplier relationships.
Trade policy adds another layer of complexity. In April 2026, U.S. Section 232 tariffs on aluminum and derivatives were revised, with rates in the range of 25 to 50 percent on full customs value for many imported aluminum articles, including extrusions that are directly relevant to exhibit manufacturing. Alongside this, an ongoing U.S. antidumping duty administrative review covering aluminum extrusions from China is examining the May 2024 through April 2025 period, with preliminary determinations addressing China-wide entity rates. These developments matter because they affect landed cost, sourcing strategy, and the relative attractiveness of domestic versus imported supply.
The strategic takeaway is not that trade risks are uniformly prohibitive, but that they require deliberate mapping. Companies with exposure to imported extrusions must evaluate tariff impact on product costing, assess alternative sourcing pathways, and consider whether near-term inventory or contract structures can buffer volatility. Companies with domestic production or flexible supply chains may find themselves better positioned to serve customers who prioritize reliability and regulatory predictability. In either case, the firms that incorporate trade dynamics into their planning early will have more options than those that discover exposure only after pricing or availability shifts.
What the Research Report Delivers for Decision-Makers
Our full market research report translates this landscape into an actionable decision framework. It is designed not as a static data reference, but as an operating companion for teams responsible for product strategy, procurement, sales planning, capital allocation, and competitive positioning. The report integrates historical analysis, forward-looking forecasts, segmentation logic, and competitive intelligence into a cohesive narrative that helps leaders answer practical questions about where demand is strengthening, where margins are under pressure, and how to align organizational priorities with market realities.
Worldwide Exhibition Stand Market
Readers can expect a detailed examination of market sizing and growth pathways across the forecast horizon, with explicit attention to the drivers behind the projected expansion and the variables that could accelerate or moderate it. The report addresses the structural role of modular systems, truss systems, and custom extrusions, and it maps how these product categories function across trade shows, events, concerts, retail displays, and related environments. Rather than presenting segmentation as an abstract breakdown, it frames each slice of the market in operational terms: what it demands from suppliers, what buying criteria dominate, and where the most meaningful value creation opportunities lie.
The competitive analysis goes beyond company descriptions to explore strategic positioning, capability differentiation, and the practical implications of recent industry moves. It contextualizes developments such as creative award recognition, the issuance of exhibit trend analyses emphasizing smarter modular builds, and exclusive distribution partnerships for LED-integrated aluminum systems. These events are not treated as isolated news items; they are interpreted as signals of how manufacturers are competing for attention, contracts, and channel advantage in a market where technology integration and design credibility increasingly influence purchasing decisions.
Material and regulatory context is woven throughout, ensuring that strategic recommendations are grounded in the real conditions shaping aluminum availability and cost. The report examines how raw material price movements affect production economics, how revised tariff frameworks alter sourcing trade-offs, and how ongoing trade reviews influence supply-chain confidence. This integrated approach allows decision-makers to connect market growth potential with the practical constraints that determine whether that potential can be captured profitably.
For executives and analysts, the report offers a structured basis for scenario planning. It supports questions such as how to prioritize regional supply flexibility, how to evaluate whether modular reuse programs can offset input cost volatility, how to position product portfolios in a market that rewards both standardization and customization, and how to interpret competitive moves as indicators of where the next wave of differentiation will emerge. In that sense, the research is meant to reduce uncertainty where it matters most: in the choices that shape capacity planning, vendor selection, pricing strategy, and long-term portfolio direction.
Strategic Takeaways for 2026 and Beyond
The aluminum exhibits market is expanding within a landscape that rewards clarity of strategy. Growth is real and measurable, but it is unfolding alongside material cost volatility, trade-policy evolution, and intensifying competition for design-led, technology-enabled exhibit solutions. Organizations that treat these forces as isolated externalities risk underestimating their impact on margins, timelines, and supplier reliability. Those that integrate them into planning will be better equipped to allocate resources, negotiate from a position of insight, and build exhibit systems that remain efficient across multiple deployments.
Several priorities stand out. First, modular and reconfigurable design is no longer a convenience feature; it is increasingly a core economic and sustainability requirement. Second, aluminum pricing and trade regulation should be incorporated into procurement and product strategy early, with explicit attention to sourcing options and landed-cost modeling. Third, competitive differentiation is shifting toward integrated capabilities, including lighting, media compatibility, rapid deployment, and engineering reliability, which means manufacturers and buyers alike must evaluate vendors on total system value rather than component price alone.
Our full report provides the deeper quantitative and qualitative intelligence needed to operationalize these priorities. It delivers the market sizing, growth trajectory, segmentation logic, competitive context, and external risk mapping required to support confident decision-making throughout 2026 and the wider forecast period. For teams seeking a clearer line of sight between market opportunity and execution strategy, the complete analysis offers the level of detail and structural insight that high-stakes planning demands.
For detailed analysis of this topic, please visit the official page: Aluminum Exhibits Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Reports Carob Chocolate Bars Market to Reach $350 Million by 2032, Growing at 7.2% CAGR
By pmarketresearch, 2026-09-16
Carob Chocolate Bars Market 2026: Strategic Intelligence for Growth Leadership
Executive Overview
The global carob chocolate bars market is entering a decisive inflection point. As consumer preferences shift decisively toward plant-based, allergen-friendly, and clean-label confectionery alternatives, carob-based bars have moved from niche retail corners to mainstream shelf space. For executive teams, category managers, and innovation directors, the 2026 landscape demands more than surface-level trend tracking. It requires a rigorous, forward-looking intelligence framework that translates macroeconomic trajectories, supply chain realities, and competitive maneuvering into executable strategy. Our latest market research delivers precisely that blueprint. By anchoring historical performance to a structured forecast horizon through 2032, this report equips leadership with the analytical clarity needed to allocate capital, time product pipelines, and outmaneuver competitors in an increasingly crowded health-conscious confectionery segment.
Protein Bars Market
Macro Trajectory: Reading the Growth Signal
The expansion curve for carob chocolate bars reflects steady, compounding momentum rather than speculative hype. Historical tracking from 2020 through 2025 reveals consistent year-over-year appreciation, with the market scaling from approximately 150 million USD to 215 million USD over that five-year window. The forecast period extends this trajectory through 2032, projecting a compound annual growth rate of 7.2 percent. This growth profile is not merely a statistical projection; it is a structural indicator shaped by ingredient substitution dynamics, retail channel evolution, and the broadening consumer acceptance of cocoa alternatives. For strategic planners, the implication is clear: scale opportunities exist, but they will be captured by organizations that align product development cycles, distribution partnerships, and pricing architectures with a market that rewards disciplined execution over speculative positioning.
Report Architecture: What Decision-Makers Will Find Inside
Our methodology is built around operational utility. Rather than delivering high-level summaries that leave implementation gaps, the report is structured to answer the questions that sit on the desks of brand strategists, supply chain directors, and market entry teams. The research framework covers:
- Historical performance tracking across the 2020–2025 baseline, establishing trend confirmation and volatility patterns that inform near-term planning assumptions.
- A forward-looking forecast model spanning the 2026–2032 horizon, with scenario-ready growth pathways designed to support budgeting, capacity planning, and market entry sequencing.
- Segment-level analysis across product formulations and distribution pathways, mapping how different consumer access points and ingredient positioning strategies contribute to overall category expansion.
- Regional market mapping that identifies where demand is consolidating, where retail infrastructure is maturing, and where cross-border supply dynamics are reshaping competitive access.
- Competitive profiling of core manufacturers and innovators, highlighting strategic positioning, product architecture, and recent commercial actions that signal where the market is heading.
- Supply-side and regulatory context, including raw material pricing signals, labeling requirements, and formulation trends that affect margin structures and go-to-market readiness.
Each analytical layer is designed to connect directly to decision processes. The objective is not to describe the market, but to make it actionable.
Carob Chocolate Bars Market
Segmentation Intelligence: Mapping Opportunity Vectors
The category is expanding across multiple product and channel dimensions, and each vector carries distinct implications for brand positioning, margin architecture, and speed-to-market. Product-type dynamics reflect a market where ingredient positioning increasingly dictates purchase behavior. Formulations anchored in organic certification and cleaner ingredient narratives continue to capture disproportionate attention from health-oriented buyers, while conventional offerings maintain relevance through accessibility and price sensitivity. Distribution-channel analysis further illustrates how the category is being absorbed into both legacy retail infrastructure and newer, experience-driven purchasing pathways. Supermarket and hypermarket networks provide the volume foundation for broad consumer reach, specialty health food retailers deliver credibility and targeted audience engagement, and online retail channels enable rapid testing, direct-to-consumer iteration, and geographic expansion without the friction of traditional shelf negotiations. Together, these segments form a multi-speed market in which growth is not uniform, but strategically navigable when mapped correctly.
Competitive Landscape: How the Field Is Shaping Up
The carob chocolate bar category remains relatively fragmented, with market concentration metrics indicating that no single coalition of players dominates overall category economics. This fragmentation is strategically important. It suggests room for differentiation, but it also means that competitive advantage will be earned through product distinctiveness, channel access, and supply chain discipline rather than scale alone. Several companies illustrate the strategic diversity currently shaping the market. Missy J's has built its identity around organic vegan carob treats engineered to be gluten-free, dairy-free, and caffeine-free, drawing on Australian organic carob and positioning clearly within clean-label snacking. The Carob Kitchen operates from a farm-to-bar philosophy in South Australia, offering milk-style, vegan, sugar-free, and no-added-sugar variants that reflect a deep integration between ingredient sourcing and product architecture. Caroboo has pursued a flavor-forward, format-diverse approach in the UK, expanding into variants such as salted caramel, mint, and orange while emphasizing compostable packaging and retail footprint growth. CarobMe has focused on organic bar formulations, including soy-free and gluten-free chocolate substitutes that appeal to allergen-conscious consumers. D&D Chocolates represents a family-run production model in the UK, emphasizing vegan, dairy-free, gluten-free, nut-free, and soya-free alternatives that target sensitive dietary requirements. Carob World, based in Portugal, underscores sustainable sourcing and cocoa-free formulation as central brand pillars. Meanwhile, The Australian Carob Co. plays a supporting role in the value chain by supplying carob products and enabling other brands to expand their carob-based bar portfolios.
Recent commercial and technical developments reinforce the pace of change. In late 2025, Caroboo secured a notable retail listing with Holland & Barrett, strengthening its presence in the UK health retail channel and signaling a deliberate push into premium-positioned distribution. Around the same period, research activity from NUS scientists demonstrated two novel flavor-boosting techniques for carob-based chocolate alternatives, pointing to a broader industry focus on taste parity as a prerequisite for mainstream adoption. In the ingredient space, the launch of a carob-derived prebiotic fiber component illustrated how functional benefits are increasingly being embedded into product narratives relevant to bars and gut-health positioning. These moves matter because they show that competition is no longer limited to taste and packaging. It now extends into flavor engineering, functional formulation, and premium retail access.
Market Dynamics: The Forces Reshaping Margin and Access
Several intersecting dynamics are redefining what it takes to compete profitably. Clean-label expectations and vegan consumption patterns continue to accelerate demand for cocoa alternatives, with formulations frequently delivering meaningfully lower sugar profiles than traditional chocolate. That reduction is not merely a nutritional talking point; it is a purchase driver and a reformulation constraint that influences ingredient selection, cost structure, and consumer perception. At the same time, supply-side conditions are introducing new planning variables. Wholesale carob pod pricing in key sourcing markets has shown notable movement, with export levels in certain segments reaching elevated levels relative to historical norms. Broader trade data also indicates a persistent gap between export and import pricing dynamics, reflecting freight, handling, certification, and channel-markup realities that manufacturers must model into cost planning. These input signals can affect margin flexibility, especially for brands that rely on specific origin sourcing or premium organic certification.
Regulatory and compliance considerations add another layer of strategic relevance. In several markets, imported plant-based food products must meet national labeling standards, including nutritional fact table requirements on packaging. While such rules vary by jurisdiction, the broader implication is consistent: international expansion and multi-market product rollouts require labeling readiness, documentation discipline, and formulation transparency that can withstand regulatory scrutiny. Brands that treat compliance as a backend task rather than a market entry prerequisite risk delays, rework, and shelf-access friction. On the consumer side, the convergence of allergen-sensitive purchasing, plant-based dietary preferences, and sugar-conscious snacking continues to expand the addressable audience for carob bars, but it also raises expectations for clarity, trust, and repeat-purchase quality. The companies that win will be those that align product claims with verifiable formulation logic and maintain consistent quality across channels.
Strategic Value for 2026 Decision-Making
In a market characterized by steady growth but increasing competitive and supply complexity, intelligence is not a luxury; it is an operating requirement. This report is designed to support three core decision priorities. First, it clarifies where growth is most likely to materialize and under what conditions, helping leadership prioritize innovation investments, channel commitments, and regional focus. Second, it contextualizes competitive behavior, enabling brands to anticipate moves in flavor expansion, retail placement, ingredient positioning, and sustainability messaging before those moves reshape shelf dynamics. Third, it integrates supply-side and regulatory considerations into strategic planning, allowing organizations to model cost exposure, prepare for labeling and import requirements, and reduce the risk of reactive decision-making.
The strategic value of this research lies in its orientation toward execution. Rather than stopping at high-level category description, the analysis connects market structure to actionable planning questions: which product narratives align with emerging demand, which distribution environments offer the strongest near-term leverage, where sourcing and input pricing may pressure margins, and how competitive differentiation can be sustained without relying solely on price. For executives evaluating market entry, product extension, channel expansion, or portfolio repositioning, the report provides the structural clarity needed to move from curiosity to commitment.
Navigating the Next Phase with Precision
The carob chocolate bars market is no longer a peripheral alternative category. It is an expanding segment shaped byIngredient-driven consumer choices, retail channel evolution, and a competitive field that is investing in taste, function, and sustainability. The organizations that will benefit most from the forecast period are those that treat growth as something to be engineered through informed positioning, disciplined cost planning, and channel-aware launch strategy. Our full market research unpacks the segment-level detail, regional context, competitive movements, and supply-side signals that leadership needs to act with confidence. The trajectory is clear. The next step is to ensure your strategy is built on the full intelligence behind it.
For detailed analysis of this topic, please visit the official page: Carob Chocolate Bars Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Metal Cutting Gas Market to Hit $7B by 2032, Growing at 5.4% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Decade Ahead: Inside the Worldwide Metal Cutting Gas Market 2026–2032
The global industrial landscape is undergoing a structural recalibration. From supply chain realignment to decarbonization mandates, manufacturing enterprises face a complex web of forces that directly influence production economics. Within this environment, the metal cutting gas market occupies a critical yet often underestimated position. As a foundational input for fabrication, maintenance, and assembly operations, the supply, pricing, and technological evolution of cutting gases increasingly determine operational resilience and cost efficiency across heavy industry. PW Consulting’s newly released Worldwide Metal Cutting Gas Market research provides a comprehensive strategic roadmap for executives navigating this competitive terrain through 2032. This analysis distills the report’s most consequential insights, emphasizing actionable intelligence for 2026 decision-making while preserving the granular data architecture that detailed procurement and investment planning require.
Market Trajectory and Macroeconomic Foundations
Historical performance and forward-looking projections establish a clear narrative of sustained growth tempered by cyclical volatility. Between 2020 and 2025, the worldwide market expanded from approximately 3,750 million USD to 4,850 million USD, reflecting robust industrial recovery, accelerated infrastructure deployment, and steady demand from fabrication-intensive sectors. The forecast window extending through 2032 indicates a compound annual growth rate of 5.4 percent, positioning the market to reach roughly 7,008 million USD by the terminal year. This trajectory signals more than incremental expansion; it reflects a structural shift in how metalworking enterprises source, optimize, and integrate cutting gases into broader operational workflows.
Historical Momentum and Forward Projections
The 2020–2025 period demonstrated remarkable resilience despite macroeconomic disruptions, logistics constraints, and fluctuating feedstock availability. Revenue progression consistently outpaced earlier baselines, underscoring the non-discretionary nature of metal cutting operations in automotive assembly, heavy equipment manufacturing, shipbuilding, and infrastructure development. Looking ahead, the forecast period anticipates acceleration driven by capacity expansions in emerging industrial corridors, modernization of legacy fabrication facilities, and increasing adoption of optimized gas blends that improve cutting efficiency while reducing consumable waste. Analysts tracking the sector note that procurement strategies are evolving from price-centric Purchasing models to integrated supply chain partnerships, where gas delivery reliability, safety compliance, and technical support carry equal weight alongside unit cost.
Structural Drivers Shaping Demand Economics
Several interlocking dynamics will define market behavior throughout the forecast window. First, the ongoing upgrading of metal fabrication capabilities in Asia Pacific and select European corridors continues to elevate baseline consumption. Second, the modernization of legacy cutting equipment toward higher-efficiency oxy-fuel and hybrid plasma configurations creates demand for specialized gas formulations that maximize flame temperature, reduce oxygen consumption, and minimize slag formation. Third, regulatory environments are tightening around hazardous air pollutants, transportation safety for compressed gases, and emissions standards in integrated steel and metal processing facilities. These regulations do not merely constrain operations; they reshape procurement specifications, incentivize cleaner-burning fuel blends, and increase the strategic value of suppliers capable of delivering compliant, technically supported gas solutions.
Metal Cutting Tools Market
Feedstock pricing remains a persistent variable. Recent market observations indicate divergent regional pricing patterns for acetylene, with European benchmarks reflecting upward pressure linked to calcium carbide supply dynamics, while North American pricing has tracked alongside varied downstream fabrication demand. Such divergences reinforce the necessity of region-specific sourcing strategies rather than one-size-fits-all procurement frameworks. Enterprises that map feedstock exposure, logistics constraints, and regional regulatory timelines into their gas purchasing architecture will secure a measurable competitive advantage.
Segmentation Intelligence and Application Realities
Effective strategy requires precise segmentation mapping. The Worldwide Metal Cutting Gas Market research decomposes the ecosystem across three critical axes: geographic distribution, gas type classification, and end-use application segments. Each layer reveals distinct demand drivers, competitive intensity, and growth vectors that general market summaries frequently obscure.
Geographic Dynamics and Regional Demand Patterns
Regional analysis within the report illuminates where industrial activity concentrates, where infrastructure investment accelerates, and where procurement frameworks diverge. The data architecture identifies Asia Pacific as the largest revenue contributor, reflecting massive fabrication output, expanding shipbuilding and offshore repair capacity, and sustained automotive and transportation manufacturing. Europe maintains a substantial share supported by mature industrial ecosystems, stringent safety and emissions standards, and ongoing equipment modernization cycles. North America rounds out the top tier, driven by heavy machinery production, defense-related fabrication, and resilient construction and infrastructure spending. Middle East and Africa, alongside Latin America, represent specialized but strategically important corridors where localized supply networks, import dependencies, and project-based demand create distinct sourcing requirements.
Importantly, the report avoids superficial regional generalizations. Instead, it maps regional demand against local feedstock availability, regulatory calendars, logistics infrastructure, and the presence of key supplier operations. This approach enables executives to evaluate market entry opportunities, assess supply chain vulnerability, and calibrate inventory strategies according to regional risk profiles rather than global averages.
Gas Type Classification and Technical Differentiation
The gas type segmentation captures a market far more diverse than legacy acetylene-centric assumptions suggest. Acetylene remains a dominant share contributor, valued for its high flame temperature and versatility across traditional oxy-fuel cutting applications. Propane follows as a widely deployed alternative, offering cost advantages and safety profile benefits for specific fabrication workflows. Propylene occupies a strategic middle ground, particularly where operators seek enhanced cutting performance with reduced oxygen consumption. Methane and natural gas segments reflect ongoing integration of utility-scale gas infrastructure into industrial fabrication environments, while specialty fuel blends represent a growing niche for precision applications requiring customized combustion characteristics.
Worldwide Metal Cutting Gas Market
Each gas type carries distinct handling requirements, storage considerations, equipment compatibility constraints, and regulatory implications. The report details how these technical differentiators influence procurement decisions, vendor selection, and in-house operational training. Executives evaluating supplier portfolios will find direct relevance in the segmentation analysis, particularly when matching gas chemistry to cutting process specifications and compliance mandates.
Application Segments and End-Market Alignment
Understanding where cutting gases are consumed unlocks clearer forecasts of demand stability, cyclical exposure, and growth acceleration. Automotive and transportation applications represent a leading consumption segment, reflecting high-volume fabrication, body-in-white cutting, chassis component processing, and aftermarket maintenance operations. Heavy machinery and industrial equipment follow closely, encompassing earthmoving equipment, agricultural machinery, and specialized industrial component fabrication that demands robustness and consistent cut quality. Shipbuilding and offshore repair form a structurally significant segment, where project-based demand peaks align with vessel construction cycles, fleet maintenance schedules, and offshore platform rehabilitation programs.
Construction and infrastructure applications provide a steady baseline driven by structural steel processing, pipeline fabrication, and civil engineering projects. Aerospace and defense represent a technically demanding segment where precision, material compatibility, and stringent quality assurance protocols elevate the importance of gas consistency and supplier technical support. The report’s application segmentation enables stakeholders to map demand volatility, identify procurement cycles, and anticipate where equipment upgrades or process optimizations will trigger gas specification changes.
Competitive Architecture and Strategic Positioning
Market concentration data indicates that the three largest competitors collectively command approximately 38.4 percent of global revenue, while the top five firms extend their combined share to roughly 52.6 percent. This concentration profile suggests a market structure where global integrators hold substantial influence, yet meaningful regional and specialized players maintain viable competitive positions through localized distribution networks, application-specific expertise, and strong customer relationships. Understanding this architecture is essential for procurement leaders evaluating supplier diversification, for investors assessing market entry barriers, and for executives planning partnership or acquisition strategies.
Global Integrators and Their Operational Footprints
Linde plc stands as a major global supplier of industrial gases, including oxygen, acetylene, propane, and specialized mixtures tailored for oxy-fuel metal cutting, plasma cutting, and laser cutting applications across metal fabrication workflows. Its worldwide operational presence enables coordinated supply across multiple regions, while technical service capabilities support complex fabrication environments. Air Liquide S.A. operates as a leading producer and distributor of cutting gases such as oxygen, acetylene, and fuel gas blends, complemented by oxy-fuel cutting equipment and integrated solutions for worldwide metal fabrication and manufacturing. The company’s position reflects deep integration between gas supply, equipment provision, and application engineering.
Air Products and Chemicals, Inc. supplies oxy-fuel cutting gases, including propylene-based cutting solutions, alongside laser and plasma cutting gases and total solutions for metal cutting applications globally. Its portfolio emphasizes performance optimization and process integration. Messer SE & Co. KGaA operates as a specialized provider of industrial gases and solutions for metal industry applications, including cutting and welding gases for fabrication, with a strong presence across Europe, the Americas, and Asia. Its regional depth and technical specialization make it a significant competitor in markets where localized service and application knowledge drive purchasing decisions.
Regional Specialists and Fuel Gas Suppliers
Beyond the global integrators, a cohort of regional and fuel-focused suppliers shapes competitive dynamics through specialized product offerings and geographic proximity. TotalEnergies SE supplies fuel gases including propane and specialized cutting gas formulations for oxy-fuel metal cutting processes, leveraging broader energy sector infrastructure and fuel distribution capabilities. Indian Oil Corporation Ltd provides Indane NANOCUT and other LPG-based cutting gases optimized for high flame temperature and low oxygen consumption in metal cutting applications, addressing regional demand with formulations designed for operational efficiency. Bharat Petroleum Corporation Limited supplies industrial and cutting gases, including LPG variants for metal cutting and fabrication in Indian and export markets, supporting both domestic fabrication and cross-border supply requirements.
Brothers Gas operates as a regional supplier of industrial cutting gases and mixtures for oxy-fuel and other metal cutting processes across Middle East and international markets, filling a strategic role in regions where localized availability and rapid response logistics influence procurement decisions. NISSAN TANAKA CORPORATION functions as a manufacturer and supplier of gases and equipment focused on metal cutting and welding applications in Japan, combining gas supply with equipment integration for technically advanced fabrication environments. ESAB, part of the Colfax group, provides cutting gases alongside welding and cutting equipment and consumables for metal fabrication worldwide, positioning itself at the intersection of consumable supply and equipment solutions.
Competitive Differentiation and Procurement Implications
The competitive landscape rewards suppliers that deliver more than volume. Technical consultation, safety compliance support, delivery reliability, formulation customization, and equipment-gas compatibility expertise increasingly differentiate market participants. Procurement teams evaluating supplier partnerships should consider how each competitor’s operational footprint aligns with regional demand, how their product portfolio maps to cutting process requirements, and how their service infrastructure mitigates supply disruption risk. The report’s competitive analysis provides a structured framework for these evaluations, enabling data-driven supplier selection rather than relationship-led assumptions.
Operational, Regulatory, and Supply Chain Context
Market behavior does not occur in isolation. Regulatory frameworks, raw material dynamics, and transportation safety requirements continuously reshape operational parameters. Recent developments highlight the practical relevance of these forces. In the United States, the Environmental Protection Agency maintains national emission standards for hazardous air pollutants applicable to integrated iron and steel manufacturing facilities, covering sinter plants, blast furnaces, and basic oxygen process shops that influence related metal processing gas usage. These standards encourage fabricators and their gas suppliers to align specifications with emissions compliance, often favoring formulations and process configurations that reduce atmospheric impact.
Simultaneously, the U.S. Department of Transportation’s Pipeline and Hazardous Materials Safety Administration oversees hazardous materials transportation regulations for compressed gases including acetylene and oxygen used in metal cutting, with ongoing research into pipeline safety and leak detection standards. Transportation compliance affects delivery scheduling, packaging choices, storage design, and risk management protocols, making regulatory tracking an operational necessity rather than a peripheral concern.
On the trade policy front, Section 232 tariffs on steel and aluminum imports underwent restructuring in April 2026, shifting application to the full customs value of certain finished products containing metals. This adjustment can influence metal fabrication costs and, indirectly, gas demand by altering the cost structure of imported components and domestic substitution incentives. Enterprises with exposure to tariff-affected supply chains should reassess procurement sourcing, inventory positioning, and gas consumption forecasts as part of broader cost and supply chain planning.
Raw material pricing adds another layer of complexity. Acetylene pricing in Europe has reflected upward movement linked to calcium carbide feedstock costs, while North American acetylene pricing has tracked alongside downstream fabrication demand with periodic increases. These dynamics underscore the importance of feedstock monitoring, contract structuring, and alternative gas type evaluation when cost volatility emerges. Suppliers and buyers alike benefit from anticipating feedstock-driven pricing shifts rather than reacting after margins compress.
What the Report Delivers for 2026 Decision-Makers
PW Consulting’s Worldwide Metal Cutting Gas Market research translates macro trends, segmentation detail, competitive intelligence, and regulatory context into a decision-ready intelligence package. The report is designed for executives who require more than headline figures. It structures information to support strategic planning, procurement optimization, supplier evaluation, market entry assessment, and risk mitigation.
Scope, Methodology, and Analytical Depth
The analysis covers historical performance from 2020 through 2025 and projects market behavior across the 2026–2032 forecast window, all expressed in million USD with a clearly documented compound annual growth rate. This temporal span enables readers to understand how past disruptions, recovery patterns, and investment cycles inform future expectations. Methodological rigor ensures that projections are grounded in observable demand drivers, segmentation logic, and competitive behavior rather than generic extrapolation.
Actionable frameworks for procurement and strategy teams
Beyond forecasts, the report provides practical frameworks that procurement and strategy teams can apply immediately. These include segmentation mapping that clarifies where demand concentrates and how it evolves, competitive profiling that distinguishes global integrators from regional specialists and fuel-focused suppliers, and regulatory tracking that highlights compliance inflection points affecting gas selection, transportation, and storage. The research also incorporates application-level insights that help align gas specifications with cutting process requirements, equipment configurations, and quality assurance standards.
For executives evaluating capital allocation, the report supports scenario planning by outlining where growth is most probable, which segments face cyclical exposure, and how regulatory or feedstock shocks could alter cost structures. For supplier relationship managers, it provides a structured lens to assess vendor capability beyond price, focusing on reliability, technical support, compliance alignment, and regional coverage. For investors and market entrants, it delineates concentration dynamics, differentiation opportunities, and the practical barriers that shape competitive viability.
Connecting data to execution
A distinguishing feature of the research is its emphasis on execution relevance. Market size and growth rates matter, but their strategic value emerges when tied to actionable choices: which gas types align with specific cutting applications, which regions present the strongest demand trajectory relative to supply risk, which competitors offer complementary capabilities, and which regulatory timelines require proactive preparation. The report is organized to facilitate these connections, enabling readers to move from awareness to action without reconstructing the analytical logic themselves.
Conclusion: Making Informed Moves in a Shifting Market
The worldwide metal cutting gas market is not a static commodity environment. It is a technically nuanced, regionally diverse, and competitively layered ecosystem in which procurement decisions, supplier partnerships, regulatory preparedness, and feedstock awareness converge to shape operational performance. The 2026–2032 forecast window presents both opportunity and complexity. Growth is sustained, but its distribution across regions, gas types, and applications requires careful evaluation. Competition is concentrated at the top yet remains dynamic through regional specialists and fuel-focused suppliers. Regulatory and trade developments introduce variables that reward proactive planning.
PW Consulting’s comprehensive market research equips executives with the intelligence necessary to navigate this environment with confidence. By combining rigorous market sizing, detailed segmentation, competitive profiling, and operational context, the report delivers a strategic foundation for 2026 decision-making and beyond. To access the full dataset, regional breakdowns, application-level analysis, and complete competitive assessments, we invite stakeholders to visit the source page and obtain the complete Worldwide Metal Cutting Gas Market research. Detailed intelligence remains the most reliable basis for strategic action, and the complete report provides exactly that.
For detailed analysis of this topic, please visit the official page: Worldwide Metal Cutting Gas Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Global Piriformis Syndrome Market to Reach $320.96M by 2032 at 5.51% CAGR
By pmarketresearch, 2026-09-16
Navigating the Piriformis Syndrome Market: Strategic Imperatives for 2026 and Beyond
The piriformis syndrome market is entering a pivotal phase of maturation, shaped by advancing minimally invasive techniques, evolving reimbursement frameworks, and a growing emphasis on multimodal pain management. As healthcare systems worldwide continue to refine treatment pathways for this complex neuromuscular condition, stakeholders require granular, forward-looking intelligence to allocate capital, position product portfolios, and anticipate competitive shifts. This analysis introduces our latest Worldwide Piriformis Syndrome Market research, a comprehensive intelligence asset designed to equip executives, investors, and clinical strategists with the decision-grade insights needed to navigate the 2026 to 2032 horizon with confidence.
Market Trajectory and Strategic Context
Over the past half-decade, the global market for piriformis syndrome interventions has demonstrated steady, structurally supported expansion. Drawing on historical performance through the base year of 2025, our research traces a consistent upward trajectory that reflects both rising diagnostic awareness and the broader shift toward targeted, outcome-driven musculoskeletal care. Looking ahead, the market is projected to reach a substantial valuation by 2032, underpinned by a compound annual growth rate that signals durable, mid-single-digit expansion across the forecast window. This growth is not accidental; it is being engineered by converging clinical, regulatory, and technological forces that are reshaping how providers approach piriformis-related pain, nerve compression, and functional impairment.
For enterprise leaders, the strategic implications are clear. The expanding market envelope creates room for differentiated value propositions, but it also raises the bar for clinical evidence, reimbursement alignment, and patient-accessibility. Companies that treat this landscape as a static commodity opportunity will likely encounter margin pressure and share erosion. Conversely, organizations that embed clinical validation, delivery-model innovation, and payer-ready documentation into their go-to-market architectures will be positioned to capture premium positioning as treatment algorithms continue to evolve.
What This Research Delivers: A Blueprint for Decision-Making
Our Worldwide Piriformis Syndrome Market study is structured as an actionable intelligence platform rather than a high-level snapshot. It integrates historical baselines, forward-looking projections, and deep qualitative context across the full treatment continuum. The report provides a rigorous examination of how conservative management, minimally invasive procedures, and surgical interventions are competing for clinical adoption, reimbursement favor, and patient preference. It further dissects the distribution ecosystem, mapping how hospitals, specialized clinics, and retail pharmacy channels are shaping access, pricing dynamics, and service integration.
Worldwide Piriformis Syndrome Market
Beyond macro-volume projections, the research delivers operational granularity that executives can translate directly into planning. Key deliverables include:
- A detailed segmentation architecture that clarifies how treatment modalities are performing across clinical settings, patient segments, and delivery pathways
- Competitive benchmarking that evaluates product positioning, procedural differentiation, and commercial strategy across leading participants
- Regulatory and reimbursement intelligence that contextualizes coding guidance, coverage determinations, and the compliance considerations influencing procedure adoption
- Clinical and practice-pattern analysis that synthesizes the role of pharmacotherapy, injectables, neuromodulation devices, and therapy-based protocols within multidisciplinary care models
- Market concentration metrics that illuminate the competitive weight of dominant players and the structural room for entrants and niche innovators
The report is built to support scenario planning. Whether the question is how to prioritize R&D investment, where to expand clinical partnerships, or how to anticipate payer behavior in the next coverage cycle, the analysis is calibrated to translate epidemiological and procedural signals into executable strategy.
Competitive Landscape: Differentiation in a Fragmented Field
The piriformis syndrome market remains comparatively fragmented, with a diverse mix of device innovators, pharmaceutical suppliers, therapy-equipment manufacturers, and specialized procedural providers competing across overlapping value chains. Concentration is moderate rather than consolidated, creating both opportunity and complexity. Incumbents must defend share across multiple modalities, while new entrants can target underserved clinical niches or delivery gaps if they bring credible evidence and clear reimbursement pathways.
Among procedural specialists, Deuk Spine Institute has advanced a distinctive outpatient surgical approach with its patented Piriformis Release technique, emphasizing a minimally invasive, permanent intervention delivered through a small incision. The company’s recent promotion of this procedure highlights a broader industry movement toward outpatient, low-downtime solutions that align with cost-conscious care delivery and patient demand for faster recovery profiles. This shift reflects an important strategic theme: procedural durability and safety narratives are becoming critical commercial assets in a space where clinicians and payers increasingly weigh long-term outcomes against upfront intervention risk.
In the pharmaceutical and injectable segment, multiple global players contribute to conservative and interventional treatment protocols. Allergan, under AbbVie, provides onabotulinumtoxinA as an adjunct to physical therapy, positioning botulinum toxin within a broader spasm-relief and nerve-compression management framework. Bayer and Novartis support the conservative pharmacotherapy backbone through NSAIDs and muscle relaxants, while Sanofi and Teva diversify access through branded and generic pain-management options. Endo Pharmaceuticals adds further depth to the pain-management supply chain, reinforcing the centrality of pharmacological intervention in initial and adjunctive care pathways.
The non-invasive and device-adjacent segment is equally active. King Brand Healthcare Products markets specialized cold and heat therapy wraps tailored to piriformis symptom relief and muscle recovery, while Omron Healthcare supplies TENS technology relevant to non-pharmacological symptom management. Recent device-oriented activity, including the promotion of wearable TENS solutions by Hinge Health, underscores a growing appetite for home-accessible, low-risk modalities that can complement clinical care and extend the patient experience beyond the point of service.
From a strategic standpoint, the competitive picture suggests that future share gains will not come from any single product category alone. The winners are likely to be those who integrate across modalities, align with clinical workflows, and demonstrate value across the patient journey. Companies that operate in silos may find their addressable market constrained by treatment algorithms that increasingly favor combined, stepped-care approaches.
Clinical Evidence, Regulation, and Reimbursement as Strategic Variables
Market growth in this space is inseparable from the evolving evidence and policy environment. Clinical research continues to refine procedural selection and comparative effectiveness. Recent trial activity, including randomized comparisons of ultrasound-guided corticosteroid injection against extracorporeal shockwave therapy, signals an intensifying focus on objective efficacy data and modality optimization. Ongoing trial listings examining post-facilitation stretch, active release techniques, and shockwave-based interventions further indicate that the field is moving toward more rigorous, protocol-level differentiation rather than reliance on anecdotal adoption.
On the regulatory and reimbursement side, policy clarity is both an enabler and a constraint. CMS billing and coding guidance for piriformis muscle injections continues to shape procedural documentation standards, while also emphasizing that certain imaging-guided needle placement methods may not consistently demonstrate additional clinical benefit over landmark-based approaches. This creates a practical compliance consideration for providers and device or injector suppliers: procedural claims and documentation strategies must align with payer expectations around necessity, efficiency, and evidence of marginal value.
Reimbursement determinations are equally influential for injectables. Medicare Local Coverage Determinations have recognized botulinum toxins as reasonable and necessary for certain off-label applications under defined criteria, including refractory piriformis syndrome when appropriate conditions are met. For pharmaceutical participants, this kind of coverage architecture can materially affect adoption ceilings, prescribing behavior, and commercial forecasting. It also reinforces the importance of building payer-facing evidence packages that address not just clinical mechanism, but real-world appropriateness and patient selection logic.
At the same time, the broader treatment philosophy is shifting toward integrated conservative care. Physical therapy approaches encompassing myofascial release, hip abductor strengthening, and neuromuscular inhibition techniques are increasingly viewed as foundational elements, often combined with pharmacotherapy or targeted injections. Surgical intervention, including laparoscopic decompression or piriformis resection, remains generally reserved for severe refractory cases after conservative and interventional options have been exhausted. This stepwise, escalation-based model matters strategically because it influences where volume accumulates, which modalities gain earlier-line adoption, and which companies benefit from downstream procedural demand.
The regulatory environment for injectables is also relevant. Multiple FDA-approved botulinum toxin type A products carry established use in muscle-related conditions applicable to piriformis syndrome management. This approval landscape does not automatically translate into uniform market performance, but it does create a structured backdrop in which clinical differentiation, administration workflows, and reimbursement compatibility become decisive competitive factors.
Strategic Takeaways for 2026 Decision-Makers
As organizations plan their 2026 moves, several themes should dominate the strategic agenda:
Worldwide Tendinitis Treatment Market
- Evidence-led positioning will increasingly separate durable franchises from transient demand. Clinical studies, real-world outcomes, and payer-acceptable documentation are becoming central to adoption velocity.
- Convergence across conservative, interventional, and device-based care is accelerating. Portfolios that can support stepped-care pathways, rather than isolated touchpoints, will be better aligned with clinical reality and reimbursement dynamics.
- Outpatient and minimally invasive options are gaining commercial attention, not only for patient convenience but also for their alignment with cost-conscious delivery models and shorter recovery expectations.
- Reimbursement architecture remains a gatekeeper. Coding guidance, coverage determinations, and documentation expectations will continue to influence which procedures and products can scale efficiently.
- Market fragmentation creates space for specialization. In a moderately concentrated landscape, targeted clinical niches, distinctive service models, and differentiated access strategies can outperform undifferentiated competition.
The strategic question for leaders is not simply whether the piriformis syndrome market is growing, but how to participate in that growth with the right mix of clinical credibility, commercial execution, and payer readiness. Our research is designed to answer that question with the precision required for high-stakes planning.
Access the Full Intelligence Suite
The market figures, segmentation behavior, competitive dynamics, and regulatory signals highlighted here represent only the opening layer of a much larger analytical framework. The complete Worldwide Piriformis Syndrome Market research goes further, delivering detailed segmentation performance, company-level profiling, forward scenarios, and operational guidance tailored to investment, product development, market-entry, and portfolio- optimization decisions. For executives who need a precise map of where value is being created and how competitive pressure is likely to evolve through 2032, the full report is the essential next step. We invite you to access the complete intelligence suite and equip your organization with the strategic clarity required to act decisively in this evolving market.
For detailed analysis of this topic, please visit the official page: Worldwide Piriformis Syndrome Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com